

“Dovish Hike” and Other Wall Street Phrases, Decoded
September 18, 2026
Wall Street has a special talent for making a quarter-point rate hike sound like an ancient prophecy.
On September 16, the Federal Reserve raised its target interest-rate range by 25 basis points, moving it from 3.50%–3.75% to 3.75%–4.00%. The decision was widely expected, and the Fed’s projections suggested roughly one more increase may be coming before rates settle around the current level.
The headline reaction? A “dovish hike.”
That sounds like a bird with a mortgage. It actually means the Fed raised rates but signaled that it may be close to finished. The hike says, “Inflation is still a problem.” The guidance says, “But nobody should assume a long march of increases is coming.”
Here is the kitchen-table glossary for translating the rest of the financial-news dialect.
Basis points: the quarter-point ruler
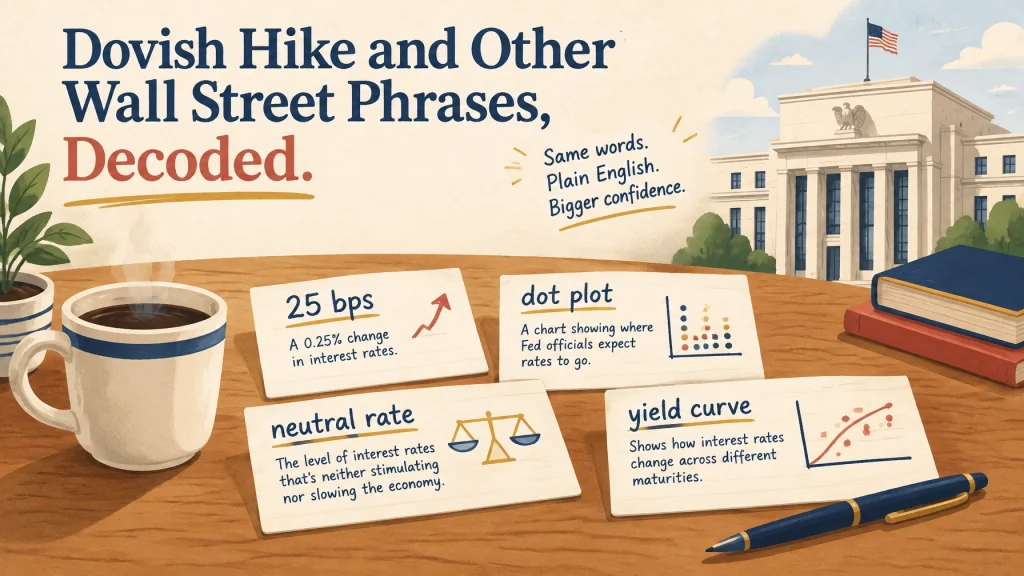
A basis point, usually abbreviated as bp or bps, is one-hundredth of one percentage point.
- 100 basis points = 1 percentage point
- 50 basis points = 0.50 percentage point
- 25 basis points = 0.25 percentage point
So when the Fed delivered a 25-basis-point hike on September 16, it raised its target range by one quarter of one percentage point.
That may sound small. It is not necessarily small for a household carrying $10,000 on a variable-rate credit card. A quarter-point increase on that balance equals about $25 more in annual interest if the entire increase is passed through and the balance stays unchanged.
For a $400,000 mortgage, the effect is more complicated because mortgages depend mainly on longer-term bond yields, not just the Fed’s overnight rate. Still, the phrase “25 basis points” is simply Wall Street’s more expensive way of saying “a quarter point.”

The dot plot: forecasts, not commandments
The dot plot is a chart showing where each Federal Open Market Committee participant expects the federal funds rate to be in future years.
The dots are anonymous. The chart does not tell you which dot belongs to which official, and it does not represent a formal vote on a guaranteed path.
After the September meeting, the median projection pointed to a federal funds rate around 4.1% at the end of 2026, which is consistent with approximately one additional quarter-point hike from the new 3.75%–4.00% range. The median projection also suggested rates could remain around that level in 2027.
That is useful information, but it is not a promise.
The Fed’s officials are making economic forecasts, not reading tomorrow’s newspaper. Inflation could surprise them. Oil prices could jump. Hiring could slow. Congress could change fiscal policy. A financial crisis could appear from behind the refrigerator like a mouse that has been paying attention to interest rates.
The dot plot tells us what officials currently believe. It does not bind them to the forecast.
The Federal Reserve’s September 16 statement is the source document. Headlines and television graphics are the translation layer: and sometimes the translation gets a little theatrical.

The neutral rate: the economy’s comfortable cruising speed
The neutral rate is the interest-rate level that neither stimulates nor slows the economy.
Think of it as a car traveling at a steady speed on a flat highway:
- Below neutral, policy is pressing the accelerator.
- Above neutral, policy is pressing the brake.
- At neutral, policy is trying not to push the economy in either direction.
The Fed’s long-run estimate has been around 3%, with recent projections nudging the estimate somewhat higher, near 3.2%. That debate matters because it changes the definition of “high.”
If the neutral rate is truly close to 3%, then a federal funds rate near 4% is meaningfully restrictive. The Fed is applying the brakes.
If the economy’s neutral rate is higher than it was in the 2010s, then a 4% policy rate may not be as powerful as many investors assume. That would help explain why economic growth and business investment can remain surprisingly sturdy even while rates are elevated.
This is the whole ballgame behind the current debate. Is the economy naturally running hotter, with higher productivity, larger government deficits, and stronger investment? Or is demand simply taking longer to cool?
The Fed is still trying to answer that question while flying the airplane.
The yield curve: short money versus long money
The yield curve compares interest rates on bonds with different maturities.
The simplest version compares:
- Short-term rates, such as two-year Treasury yields
- Long-term rates, such as 10-year or 30-year Treasury yields
A normal yield curve slopes upward. Investors demand a higher return to lend money for ten years than for two years because more can go wrong over a longer period.
An inverted yield curve slopes downward. Short-term rates are higher than long-term rates. That often means investors expect slower growth, lower inflation, or future rate cuts.
A steepening yield curve means the gap between short and long rates is getting larger. It can happen in different ways:
- Short rates fall while long rates stay put
- Long rates rise while short rates stay put
- Both move, but long rates rise faster
A steepening curve is not automatically good or bad. If it steepens because inflation expectations are rising, that can be uncomfortable. If it steepens because short rates are expected to fall as inflation cools, it may reflect a softer economic landing.
The important point: the Fed directly controls the overnight policy rate. It does not directly set the 10-year Treasury yield or your mortgage rate.

“Dovish hike”: the market’s favorite compromise
A dovish hike is a rate increase paired with relatively gentle forward guidance.
The September 16 decision fits the phrase because the Fed raised rates, but the projections did not point to an aggressive series of additional increases. The median outlook suggested one more hike, followed by a period of holding rates steady.
That is less threatening than a message saying, “Inflation is unacceptable, and more hikes are coming at every meeting until the economy begs for mercy.”
A hawkish Fed emphasizes inflation risks and signals that rates may need to rise further or stay high for longer.
A dovish Fed emphasizes economic risks, employment, and the possibility that rates can stop rising: or eventually fall.
The September move had both flavors:
- Hawkish action: The Fed raised rates because inflation remains above its 2% target.
- Dovish guidance: Officials did not signal an open-ended campaign of increases.
This is why markets often like a dovish hike. Investors get confirmation that inflation is being taken seriously without receiving a fresh bucket of rate increases.
Soft landing: slowing down without crashing
A soft landing is the economic version of reducing speed without driving into a ditch.
The Fed wants inflation to return toward 2% while unemployment remains relatively low and economic growth continues. That is difficult because higher interest rates reduce borrowing, spending, housing activity, and business investment.
The ideal outcome looks something like this:
- Inflation cools.
- Wage growth becomes sustainable.
- Hiring slows but does not collapse.
- Consumer spending remains functional.
- The Fed eventually stops pressing the brake.
The September projections described an economy that was still expanding, with unemployment expected to remain around 4.1% while inflation gradually eases. That is the soft-landing argument.
The opposing argument is that monetary policy works with long and unpredictable delays. A hike that looks harmless today may hit construction, credit cards, small businesses, and household budgets months from now.
“Priced in”: why good news can produce no celebration
When traders say a rate hike was “priced in,” they mean investors already expected it before the announcement.
That explains one of Wall Street’s most confusing reactions: the Fed announces a rate increase, and stocks rise.
The announcement itself was not good news. It was simply not worse than expected.
Markets react to the difference between:
- What investors expected
- What actually happened
The September 16 hike had been broadly anticipated. Therefore, the important question was not “Did the Fed hike?” It was “What did the Fed say about the next hike?”
If investors expected three more increases and the Fed suggested one, markets might rally. If investors expected one and the Fed hinted at four, markets could fall sharply.
“Priced in” is the financial equivalent of buying a birthday present after everyone has already seen the receipt.

The September 16 cheat sheet
Keep this nearby the next time a financial headline arrives:
| Wall Street phrase | Plain-English translation |
|---|---|
| 25 basis points | One quarter of one percentage point |
| Dot plot | Anonymous Fed officials’ rate forecasts, not a promise |
| Neutral rate | The rate that neither speeds up nor slows the economy |
| Yield curve | A comparison of short-term and long-term interest rates |
| Dovish hike | Rates went up, but the Fed may be nearly finished |
| Hawkish | More worried about inflation; more rate increases are possible |
| Dovish | More worried about growth and jobs; fewer hikes or cuts are possible |
| Soft landing | Inflation falls without a major recession |
| Priced in | Investors already expected the news |
The practical lesson is simple: do not stop at the headline. Read the action, then read the guidance. The September 16 hike raised the cost of money today, but the Fed’s forecast tells us how much more pressure it believes the economy can handle.
For more plain-English economic commentary, visit the Regular Guy Economics blog or listen through the podcast page.
Disclosure: This article is for informational and educational purposes only. Regular Guy Economics is not a financial advisor, and this content is not investment advice. Economic conditions and market outcomes can change quickly. Make financial decisions based on your own circumstances and, when appropriate, consult a qualified professional.
Be mindful, be watchful and good luck.