

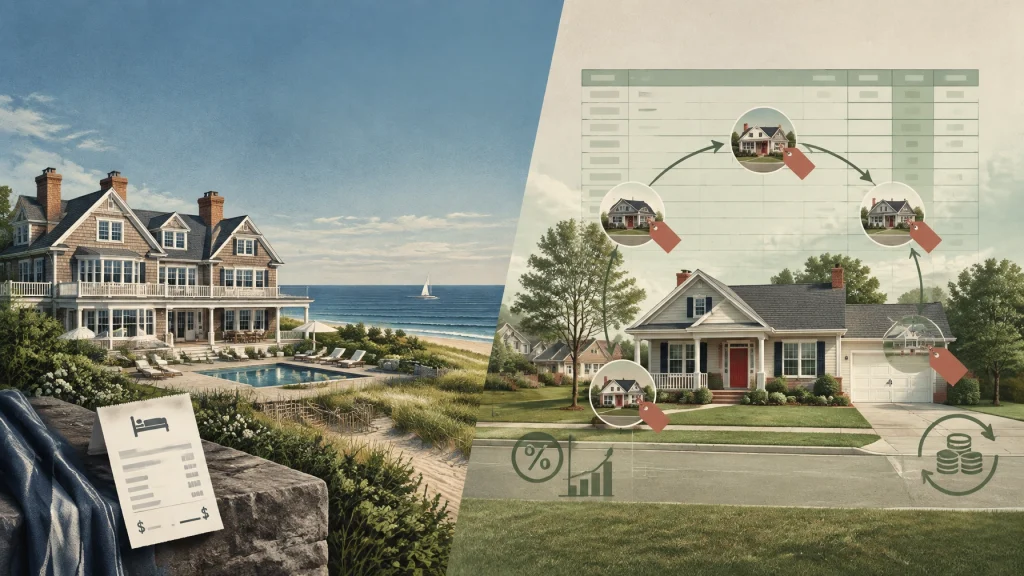
A real estate appraisal can be perfectly competent and still tell you almost nothing about whether a property is a good investment.
That is the problem.
For an owner-occupied home, the sales-comparison approach is familiar: find similar houses, look at what they sold for, make adjustments for size and condition, and arrive at a value. The method is accepted because buyers generally think that way. They ask, “What are similar houses selling for?” They do not usually ask, “What cap rate am I getting on the school district?”
But when that same appraisal is treated as an investment value, collateral value, or balance-sheet asset, the arithmetic gets uncomfortable.
Comparable sales are ultimately circular. One house is worth $1 million because another house sold for $1 million. That other house was worth $1 million because a previous house sold for $1 million. The process can create a market consensus, but it does not create a fundamental anchor.
For an income-producing property, the anchor should be income.
The basic formula is simple:
Value = Net Operating Income ÷ Capitalization Rate
That is not a prediction. It is arithmetic. And when the arithmetic is applied to expensive residential real estate, especially at the upper end, the appraisal number often floats far above what the property can economically support.
The math that should come before the comps
Start with the gross rental income. Then subtract the costs required to operate and preserve the property.
The calculation should include:
- Property taxes
- Insurance
- Property management, usually about 8% to 10% of gross rent
- A vacancy allowance, roughly 8% in a conservative model
- Repairs and capital maintenance
The maintenance reserve is where many household balance sheets quietly cheat.
Maintaining a property in its current condition requires capital. A reasonable reserve can be 2.0% to 2.5% of replacement cost every year. Replacement cost means what it would cost to rebuild the structure, not the market value of the land and not the total sale price.
A $3 million structure therefore requires a reserve of about $67,500 annually at a 2.25% rate. That money may not be spent every year. Roofs, windows, boilers, siding, pools, septic systems, landscaping, and kitchens do not conveniently fail on an annual schedule. But the cost is real, and eventually somebody pays it.
Most homeowners do not put that money aside. That does not make the liability disappear. It turns it into deferred maintenance.
After these expenses, what remains is Net Operating Income, or NOI.
Mortgage payments are not included in NOI. Cap rate measures the unlevered yield of the property before financing. Debt service comes afterward.
The income value is then:
Property value = NOI ÷ cap rate
The sales-comparison method asks what buyers recently paid. The income method asks what the asset earns. Those are not always the same question.

The fictional transaction test
There is another useful way to test a valuation: ask how much debt the property’s income can actually support.
Lenders use a version of this through the debt-service coverage ratio, or DSCR. A common standard is 1.25x. That means the property’s income must cover its carrying costs by 25%.
In plain English, if a property produces $300,000 of rent, the maximum carrying cost supported by the test is:
$300,000 ÷ 1.25 = $240,000
From there, subtract taxes, insurance, and maintenance. The amount left is what can support debt service. Calculate the loan that debt service can carry, then add the buyer’s 20% down payment.
The result is the property’s income-supportable price.
It is a fictional transaction because it asks what would happen if the property had to stand on its own as an investment. No prestige premium. No billionaire’s second home. No “they aren’t making any more land” speech delivered over a cocktail.
Just rent and expenses.
Example one: the Hamptons
Consider a Hamptons home that rents for $300,000 during the summer season.
The price may be $10 million to $15 million. The rental income is still $300,000.
Use $85,000 for property taxes, the midpoint of a $50,000-to-$100,000 range. East End effective property-tax rates can run roughly 0.4% to 0.7% of market value, depending on the property and municipality.
Assume:
- Gross rent: $300,000
- Property taxes: $85,000
- Maintenance reserve: $67,500
- Insurance: $25,000
The maintenance reserve assumes a $3 million replacement cost at 2.25%.
Under the simplified 1.25x carrying-cost test:
- Maximum total carrying cost: $240,000
- Taxes, maintenance, and insurance: $177,500
- Amount left for debt service: $62,500
At 6.5% on a 30-year loan, $62,500 of annual debt service supports approximately $824,000 of borrowing. Add a 20% down payment, and the income-supportable price is approximately:
$824,000 ÷ 80% = roughly $1.03 million
The comparable-sales appraisal says $10 million to $15 million.
That is a gap of roughly ten to fifteen times.
And this calculation is generous. It has not yet deducted professional management or an explicit vacancy allowance. Add management at 9% of gross rent: $27,000-and an 8% vacancy allowance, $24,000-and the full operating NOI falls to approximately $71,500.
At a $15 million market price, that produces a net cap rate below 0.5%. Even using the more generous pre-management figure of $122,500, the implied cap rate is only about 0.8%.
The Brown Harris Stevens Q2 2026 Hamptons report shows the market clearly: the median sale price reached $2.5 million, up 31.9% year over year, while the average reached $3.84 million. Inventory was limited, and luxury transactions pulled the average upward.
Those are real sale prices. They are not necessarily rational investment prices.
Many Hamptons buyers are lifestyle buyers. They want the beach, the village, the status, and a place to spend August. Many pay cash. They are not measuring their purchase against a 6% cap rate.
That is precisely the point. The appraisal method is borrowing credibility from a market that never claimed to be organized around return on invested capital.

Example two: Nashville
Nashville is a better test because it is not primarily a trophy market.
Using the figures supplied for a typical Nashville home:
- Median home price: roughly $429,000 to $444,000
- Median rent: about $1,780 per month
- Annual rent: $21,360
- Property taxes: $3,000
- Insurance: $1,800
- Maintenance reserve: $6,750
The maintenance reserve assumes a $300,000 replacement cost for the structure at 2.25%.
The 1.25x test gives:
- Maximum total carrying cost: $21,360 ÷ 1.25 = $17,088
- Taxes, insurance, and maintenance: $11,550
- Amount left for debt service: approximately $5,500
At 6.5% for 30 years, that supports a loan of roughly $73,000. Add 20% down, and the income-supportable price is approximately:
$73,000 ÷ 80% = about $91,000
The median sale price is around $429,000.
That is nearly a five-times gap.
Again, this is a generous calculation. Once management and vacancy are included, the property’s full NOI is closer to $6,400. At the market price, that is a net cap rate of roughly 1.5%. Using the more conservative debt-service figure of $5,500, the implied yield is about 1.3%.
At a 5.5% cap rate, the same income supports a value near $100,000 to $120,000-not $429,000.
For context, Northmarq’s Hampton Roads market report reported multifamily cap rates around 5.25% to 5.5%. That is not a perfect comparison with a single-family Nashville house, but it demonstrates the difference between a functioning income market and a residential market priced primarily by owner-occupier demand.
Nashville rents have also been softening in 2026 while home values have remained far above the income they generate. Zillow’s Nashville housing data places typical home value around $429,000, while broader rent data shows only modest changes or slight declines.
When the income side softens, the price side eventually has to explain itself.

Illusory assets on the household balance sheet
Household real estate is generally carried at market value. But market value is established by comparable sales, and comparable sales are heavily influenced by credit availability, scarcity, and sentiment.
That means the asset side of the household balance sheet is often a consensus opinion rather than a measurement of productive income.
This matters because the house is also collateral.
Equifax data reported that U.S. home-equity lines of credit reached $444.8 billion in June 2026, up 12.5% year over year. Homeowners are tapping equity rather than refinancing their low-rate first mortgages.
When the appraisal rises, borrowing capacity rises. When the appraisal falls, the debt does not politely shrink with it.
This is the same issue appearing elsewhere in the economy: assets valued on a story, debt written against those assets, and investors assuming the story will remain intact. A balance sheet can look healthy right up until the last marginal buyer changes his mind.
There is an honest counterargument.
An owner-occupied home is not necessarily an income asset. Its return includes the value of living there, avoiding rent, choosing a school district, shortening a commute, and enjoying security of tenure. Those benefits are real. A family does not need a 5.5% cap rate to justify a home.
But the moment the property is treated as an investment (a rental, a HELOC collateral position, a fund allocation, or a balance-sheet asset) the income math matters.
And the income math does not work.
Why the gap persists
The gap between price and income can survive for years because several forces support it:
- Credit availability sets the ceiling on prices more than rents do.
- Zoning and supply constraints limit new construction.
- Owner-occupiers are not yield buyers.
- Institutional and foreign capital may be parking money rather than chasing income.
- The tax code subsidizes leverage, mortgage ownership, and rental depreciation.
- Appraisals are backward-looking and validate the last transaction.
None of this predicts a crash. It does explain why a high appraisal should not be confused with a productive asset value.
A house can be worth what somebody will pay for it. It can also be worth far less if the financing disappears, the buyer pool shrinks, or the rental income becomes the only available test.
That is the gap worth watching.
Be mindful, be watchful and good luck.
This article is for educational purposes only, is not investment advice, and should not be used as a substitute for advice from a qualified real estate, tax, lending, or investment professional.