

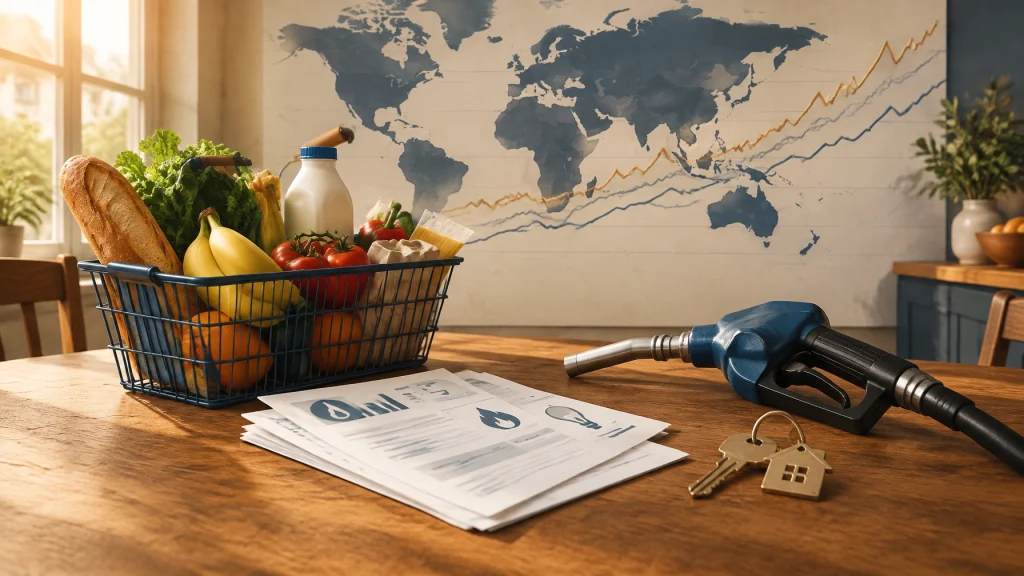
The cost-of-living crisis was not a single problem. It was a pileup.
Energy became more expensive. Food followed. Shipping costs jumped. Housing absorbed larger portions of household income. Interest rates rose to fight inflation, which made mortgages, car loans, credit cards, and business borrowing more expensive.
Governments then faced an ugly question: How do you help people pay the bills without making the inflation problem worse?
The International Monetary Fund is releasing a series of reports that includes a chapter on the lessons learned from the cost-of-living crises. The IMF has also flagged a rise in global bond yields across both advanced and emerging economies.
That combination matters. The first question is how governments responded when families were priced out. The second is how they paid for those responses. A government can promise relief with a straight face, but eventually the bond market sends the bill.
This is a preview, not the final report card. The follow-up will compare these expectations with what the IMF’s chapter actually says. The report may reach different conclusions, and that is precisely why the exercise is useful.
Price caps: immediate relief, delayed reality
Europe’s energy crisis produced the clearest example of price caps and broad subsidies. Governments limited household energy bills, reduced taxes on fuel, subsidized electricity, or paid suppliers to hold prices below market levels.
For families facing a heating bill that suddenly doubled, this was not theoretical. It was the difference between keeping the heat on and choosing between heat and groceries.
The problem is that a price cap does not make the underlying cost disappear. It transfers the cost to taxpayers, energy companies, or future budgets. It can also weaken the incentive to conserve energy. If the price at the meter does not reflect the cost of producing or importing energy, households have less reason to turn down thermostats, improve insulation, or switch to cheaper alternatives.
Some programs were targeted at lower-income households. Those were easier to defend. Others applied broadly, including to households that could have absorbed the increase. Universal subsidies are politically popular because everyone sees the benefit, but they are expensive because everyone gets the benefit.
This is the kitchen-table version: if the grocery store raises the price of bread and the government pays every customer part of the difference, the checkout line feels better. But the money still has to come from somewhere. If it is borrowed, the interest arrives later.

Fuel subsidies: popular, costly, and hard to remove
Emerging markets have long used fuel subsidies to keep gasoline, diesel, and cooking fuel affordable. During the crisis, many expanded those programs or delayed price increases.
The political logic is obvious. In a lower-income country, fuel prices affect nearly everything. Transportation gets more expensive, food distribution costs more, and workers spend more getting to work. A fuel subsidy can prevent an immediate shock from becoming a social emergency.
The economic problem is that fuel subsidies often benefit higher-income households more than poorer households because wealthier families generally consume more fuel. A household with several vehicles receives more support than a family that relies on public transportation.
Subsidies also create budget exposure. When the international price rises, the government must spend more to preserve the domestic price. That can produce a dangerous cycle: more borrowing, higher interest costs, less money for health and education, and eventually a forced subsidy withdrawal when the budget runs out of room.
The honest assessment is not that all subsidies are foolish. In an emergency, a temporary subsidy can buy time. The mistake is pretending that temporary relief has become a permanent entitlement.
Windfall taxes: revenue with a warning label
When energy producers earn unusually large profits during a supply shock, windfall taxes become politically attractive. The argument is straightforward: consumers are suffering, producers are benefiting, and the government should capture part of the unexpected gain to fund relief.
Several countries used versions of this approach. The policy can raise revenue without directly suppressing the price consumers see. That is an important advantage. A household still sees that energy is expensive, while the government uses part of the producer’s extraordinary profit to help vulnerable households pay the bill.
But windfall taxes are not free money. They are complicated to define and administer. What counts as a normal profit? What counts as a windfall? How are investment expenses treated? Does the tax apply to old production, new production, or both?
There is also an investment question. If companies believe successful investment will be heavily taxed whenever prices rise, they may invest less in future supply. That risk is especially important in energy, where new production and infrastructure can take years.
The reasonable conclusion is that a temporary, clearly defined tax can raise useful revenue. A permanent or unpredictable tax can damage investment and reduce confidence. The tax code is not a magic ATM.
Direct transfers: the cleanest tool in the box
Targeted cash assistance was generally the most efficient response because it helped people without changing the price signal for everyone else.
Instead of making electricity cheap for every household, a government can send additional money to households that cannot afford the bill. Instead of subsidizing every gallon of gasoline, it can provide temporary support to people with low incomes or high transportation needs.
This approach has two advantages.
First, it is better targeted. The household that is genuinely at risk receives more help than the household with a large income and a large house.
Second, it preserves the incentive to adjust behavior. If energy remains expensive, households and businesses still have a reason to conserve, improve efficiency, and search for alternatives.
The challenge is administrative. Governments need accurate income information, functioning payment systems, and a way to identify people who are vulnerable but not already enrolled in a benefits program. In countries with weak administrative systems, a theoretically efficient transfer may arrive too slowly or miss the people who need it.
Still, the basic idea is strong: help the person, not every unit of energy.
The IMF has repeatedly emphasized temporary and targeted fiscal support. Its Fiscal Monitor provides the broader framework for understanding why fiscal capacity matters when governments face an expensive shock.
Interest-rate hikes: necessary medicine for the wrong disease
Central banks raised interest rates because inflation was spreading through the economy. Higher rates reduce borrowing, slow demand, support the currency in some cases, and help keep inflation expectations from becoming permanently embedded.
But the crisis was not caused entirely by excessive demand. A shipping lane cannot be repaired with a higher policy rate. A shortage of natural gas does not disappear because mortgage rates rise. A drought does not respond to a central bank announcement.
That is the classic dilemma: central banks must respond to inflation even when much of the original problem came from supply.
The result is blunt. Higher rates can reduce demand enough to bring prices under control, but they also make it harder for families to buy homes, harder for businesses to expand, and more expensive for governments to refinance debt.

This is why fiscal support must be targeted. Broad stimulus can force the central bank to raise rates further. Targeted support protects vulnerable households while creating less additional demand.
Wage and price controls: the historical warning sign
Governments have tried wage and price controls many times. The results are usually disappointing.
A legal price ceiling can hold down the posted price, but it cannot guarantee that goods remain available. If sellers cannot cover their costs, they reduce supply, lower quality, or find ways around the rule. Shortages and unofficial markets follow.
Wage controls create a similar problem. If wages are held below what workers require, labor moves elsewhere or disappears from the formal market.
Controls may be useful for a narrow emergency involving a specific product, but they are generally the least successful long-term tool. They treat the visible price rather than the underlying shortage.
Reserves, efficiency, and demand reduction
Strategic reserve releases can help when a temporary supply disruption creates an unusually sharp price spike. Releasing oil from a reserve can add supply quickly. Food stockpiles can help during a harvest failure or import disruption.
But reserves are finite. They are a bridge, not a new source of production.
Demand reduction campaigns are less dramatic but often more durable. Asking households to reduce energy use, improving building efficiency, and subsidizing insulation or heat pumps can lower future bills without creating a permanent government obligation.
Efficiency subsidies can be worthwhile when they produce lasting savings. The important question is whether the program buys a durable reduction in energy use or simply lowers today’s bill while leaving tomorrow’s problem untouched.
The bond market sends the second invoice
The relief debate is only half the story. The other half is the cost of borrowing.
When governments spend heavily to cap prices, subsidize fuel, send transfers, or support businesses, they often issue more debt. At the same time, inflation pushes investors to demand higher yields. Higher yields increase the cost of issuing new debt and refinancing old debt.
That turns interest into a larger budget category.
Imagine a household that adds a large balance to a credit card during an emergency. The first problem is the emergency spending. The second problem arrives when the interest rate resets. The household now has less money for rent, food, repairs, and savings because more of each paycheck goes to interest.
Governments face the same arithmetic, only with larger numbers and better stationery.

Higher yields can create a doom loop in countries with weak fiscal positions:
- A crisis leads to more government borrowing.
- More borrowing raises concerns about debt sustainability.
- Investors demand higher yields.
- Higher yields increase debt-service costs.
- The government has less room for the next emergency.
Emerging markets face additional risks when debt is denominated in a foreign currency or when domestic banks hold large amounts of government debt. Advanced economies have deeper markets and stronger institutions, but high debt still makes them vulnerable to higher refinancing costs.
The IMF’s Global Financial Stability Report tracks these broader financial conditions, including the way higher yields affect markets beyond the country where rates first rise.
The United States was part of the experiment
This is not a foreign postcard. The United States ran its own version of the same experiment.
Strategic reserves were released. Interest rates were raised. Subsidies were debated. Households received support during the broader emergency. Energy companies earned unusually large profits while consumers faced higher prices.
The results were mixed because every tool solved one problem while creating another.
Reserve releases helped cushion supply. Rate hikes helped cool inflation but damaged borrowing affordability. Transfers protected households but added to fiscal pressure. Subsidy proposals offered relief but raised questions about cost, targeting, and incentives.
That is the real lesson. There is no free lunch in a supply shock. The policy choice is about deciding who receives relief, who pays for it, how long the support lasts, and whether the program encourages the economy to adapt.
The forthcoming IMF chapter should help answer the comparative question: Which countries protected vulnerable households most effectively? Which policies reduced hardship without prolonging inflation? Which programs were affordable, and which simply moved the bill into the future?
The follow-up will test this preview against the report itself. The conclusions may differ from the expectations laid out here. That is not a problem. It is how analysis is supposed to work.
The world got priced out. Now it has to decide which lessons are worth keeping.
Be mindful, be watchful and good luck.
This article is for educational purposes only and is not investment advice. Economic conditions and financial markets change quickly. Consult a qualified financial professional before making investment, borrowing, or other money decisions.