

October 8, 2026
The economic news has been mostly gloom: weak hiring, cautious companies, expensive borrowing, and consumers wondering whether the next paycheck will stretch as far as the last one.
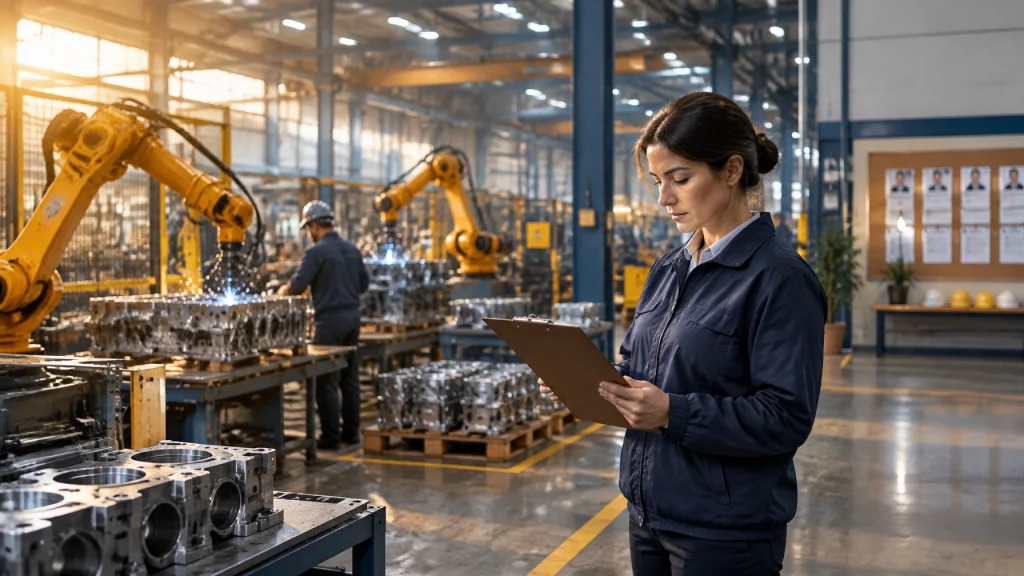
Then manufacturing showed up with a different story.
The ISM Manufacturing PMI came in at 54.5 for September. That is not a rounding error. It is not a barely-above-water reading. It indicates that American manufacturing expanded during the month.
The important word is expanded. Not boomed. Not returned to the industrial glory days of 1956. But expanded.
That creates an awkward question for anyone describing the entire economy as frozen: Are factories actually doing okay?
The honest answer is yes, at least for now. The second honest answer is that the factory story is more complicated than one encouraging number.
First, what is a PMI?
PMI stands for Purchasing Managers’ Index. The name sounds like something designed to keep ordinary people away from the conversation, but the basic idea is simple.
Every month, the Institute for Supply Management surveys purchasing and supply managers at manufacturing companies. These are the people who buy the steel, chips, chemicals, components, packaging, machinery, and other inputs that factories need to operate.
They are close to the action. A chief executive may have a twelve-month strategy. A purchasing manager knows whether orders are arriving, whether suppliers are late, whether inventories are rising, and whether the production floor is about to get busier or quieter.
The survey asks whether various conditions are:
- Better than last month
- Worse than last month
- About the same
Those answers are converted into a diffusion index. The dividing line is 50.
- Above 50 means more respondents reported improvement than deterioration.
- Below 50 means more respondents reported deterioration than improvement.
- Exactly 50 means the answers are balanced.
So September’s 54.5 means manufacturing conditions improved on balance. It does not mean that every factory expanded, every product line grew, or every worker received a raise. It means the industry had more forward momentum than backward momentum.
The ISM’s official PMI reports are useful because they arrive early in the month and provide a quick look at business conditions before many harder government statistics are available.

The details behind the 54.5 matter
The headline is encouraging, but the internal numbers tell a more useful story.
September’s reported components included:
- New orders: 55.3
- Production: 56.7
- Employment: 52.7
- Backlog of orders: 56.4
- Prices: 77.9
That is a fairly solid combination of demand, production, and unfinished work. New orders above 55 suggest that customers are placing more orders across the sector. Production at 56.7 says factories are responding. Backlogs at 56.4 indicate that some manufacturers have more work than they can immediately complete.
The employment component also moved above 50. That matters because it suggests manufacturers were not simply working through old orders while quietly cutting payrolls. Purchasing managers reported modest improvement in factory employment as well.
But then comes the unpleasant part: prices registered 77.9.
A factory can be busy and still be under pressure. Strong activity does not automatically translate into comfortable profit margins. If metals, energy, components, transportation, and labor are getting more expensive, manufacturers have to decide whether to raise prices, accept lower margins, or delay investment.
The September PMI therefore says something more nuanced than “manufacturing is back.” It says:
Demand is improving, production is active, backlogs are building, and input costs are becoming a problem.
That sounds less like a miracle and more like a real economy.
Why can factories look healthy when jobs look terrible?
Manufacturing represents only about 8% of U.S. employment. That is important context.
A factory sector can be busy while the broader labor market struggles because most American jobs are in services: health care, education, retail, restaurants, finance, transportation, government, and professional services.
Those sectors can freeze hiring even while factories are buying equipment and filling orders.
There is also a timing problem. Factories often respond to demand in stages:
- Orders increase.
- Purchasing managers buy more materials.
- Production schedules rise.
- Backlogs build.
- Overtime increases.
- Only then does management decide whether permanent hiring is necessary.
A company can run a production line at high utilization while keeping its headcount flat. It can add a shift using overtime, temporary labor, automation, or better scheduling. That produces a strong PMI without producing a giant payroll increase.
This is why a healthy manufacturing survey can coexist with a weak overall jobs report. The survey is measuring the direction of business activity. The payroll report is measuring actual employment. Those are related, but they are not the same thing.
There is another important warning: a PMI measures direction and breadth, not the absolute level of output.
A reading above 50 means conditions are improving compared with the previous month. It does not prove that factory output has returned to its level three years ago. If production fell sharply in the past and then rises modestly for several months, the PMI can remain above 50 while the industry is still below its old peak.
Think of a person climbing out of a hole. Moving upward is good news. It does not mean the person is already standing on the roof.

Is this a broad industrial recovery, or an AI boom with a factory accent?
This is the central question.
One possibility is that American manufacturing is experiencing a genuine industrial recovery. New orders are improving, production is rising, backlogs are growing, and companies are seeking workers. That would be a meaningful change from the long period of manufacturing weakness.
The other possibility is that a narrow group of industries is pulling the entire index higher.
AI-related capital spending, data-center construction, electrical infrastructure, semiconductor equipment, and defense have become enormous sources of demand. Those industries consume steel, concrete, power equipment, cooling systems, networking gear, construction services, and specialized machinery.
A data center does not arrive at the factory door labeled “technology.” It arrives as orders for thousands of physical inputs.
That can lift manufacturing even while traditional business investment remains soft.
An earlier Regular Guy Economics analysis found that non-tech capital spending had been falling year over year for six straight quarters, while AI investment continued to attract an outsized share of corporate budgets. The concern is not that AI spending is imaginary. The concern is that it may be crowding out other investment.
A company has only so much access to cash, credit, construction labor, electrical capacity, and executive attention. If the priority becomes an AI data center, a factory modernization project, a warehouse expansion, or a conventional equipment upgrade may get pushed into next year.
That makes the 54.5 harder to interpret. It may be the first sign of a broad industrial cycle, or it may be evidence that one extraordinarily powerful engine is pulling a mostly tired vehicle uphill.

The labor evidence is better than the doom narrative admits
There is, however, a counterweight to the AI explanation.
Manufacturing labor data has been genuinely decent. Dismissals have been at multi-year lows, while manufacturing vacancies have reached their highest level since December 2023. That combination matters.
If the PMI were being lifted entirely by a narrow capital-spending story, manufacturers might still be cutting workers aggressively. Instead, the labor data suggests that employers are holding onto workers and, in some cases, looking for more.
The Bureau of Labor Statistics’ JOLTS data tracks job openings, hires, and separations. It is not a perfect real-time measure, but it helps separate a temporary survey improvement from actual employer behavior.
Low dismissals suggest manufacturers do not want to lose the workers they already have. That makes sense. Skilled industrial workers are not sitting around in a warehouse waiting for a company to order them. Training takes time, and replacing experienced employees can be expensive.
High vacancies suggest that at least some companies see enough future demand to keep searching for labor.
That is real evidence of strength.
It is not proof that every manufacturing town is thriving. It is not proof that the sector can absorb millions of displaced service workers. It does suggest that the factory economy is healthier than the broadest doom headlines imply.
The kitchen-table conclusion
The 54.5 PMI should not be treated as a reason to celebrate a new industrial golden age. It should also not be ignored because the broader jobs market looks weak.
The most reasonable interpretation is this:
- Manufacturing activity is expanding.
- New orders and backlogs are providing genuine support.
- Factory employment is holding up better than expected.
- Input prices are a serious problem.
- AI, data centers, and defense may be doing too much of the lifting.
- The PMI shows improvement in direction, not necessarily a full recovery in level.
- The next few months will reveal whether the strength spreads beyond the favored sectors.
The economy is not one giant machine moving at one speed. It is a collection of machines, many of them misfiring, some of them idling, and a few running hot enough to make the whole building shake.
Factories are doing okay. That is worth saying plainly.
The harder question is whether they are doing okay because the entire industrial base is healing, or because one very expensive AI boom is buying an enormous amount of steel.
Be mindful, be watchful and good luck.
This article is for educational and informational purposes only. It is not investment advice, a recommendation to buy or sell any security, or a substitute for professional financial guidance. Talk with a qualified professional before making investment or other money decisions.