

The promise was simple enough to fit on a campaign sign:
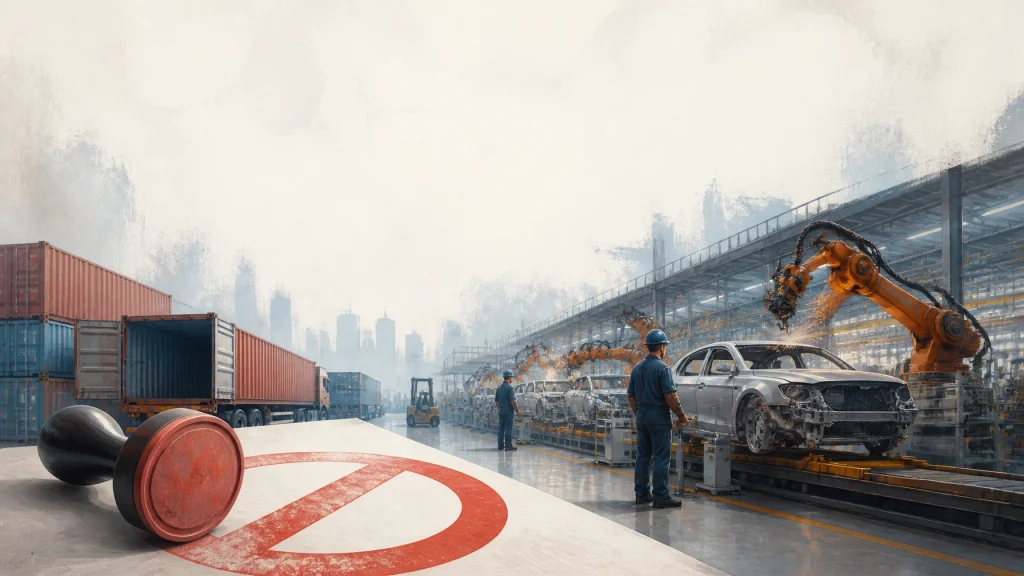
Put tariffs on imported cars and parts, make foreign goods more expensive, and American factories will hire American workers.
That story has obvious appeal. A factory opens, a worker gets a steady paycheck, and a town gets its economic heartbeat back. It is the kind of kitchen-table economics that sounds like common sense.
Unfortunately, factories are not magic vending machines. Put a tariff into the production system and jobs do not automatically fall out the other side.
The early evidence from the 2025 auto tariffs is remarkably clear: the tariffs did not produce a broad American automotive hiring boom. A study tracking 18 automakers and major suppliers found that new U.S. job postings fell approximately 8% after the tariffs took effect.
That is not exactly the industrial renaissance promised in the speeches.
The headline number: postings fell 8%
The study tracked a consistent group of 18 automakers and suppliers. It compared new job postings in the year before the tariffs with the year after:
- April 2024–March 2025: 36,315 new U.S. postings
- April 2025–March 2026: 33,275 new U.S. postings
- Change: down roughly 8%
Job postings are not the same thing as confirmed hires. A company can post a job and never fill it. It can also hire workers through recruiters, referrals, or internal transfers without posting publicly.
Still, postings are a useful thermometer for employer demand. When companies expect stronger production, they generally advertise more positions. When they are worried about costs, sales, or the rules changing again next month, they tend to leave the hiring brake engaged.
The broader comparison is also telling. Among the same companies, postings in Germany fell about 13%, while postings in Canada rose roughly 16%: although Canada’s increase came from a much smaller base.
The key point is not that every plant moved in the same direction. The point is that the United States did not experience the large, unmistakable surge in automotive hiring that tariffs were supposed to create.
The data come from PredictLeads’ analysis of automotive hiring after the tariffs.

Why protection did not equal employment
A tariff is a tax on imports. It can protect a domestic producer from foreign competition, but it also raises the cost of imported components and raw materials.
An American auto plant may assemble a vehicle in Michigan, Ohio, or Alabama, but that does not mean every part inside the vehicle was made there. Modern vehicles are rolling supply chains. Components can cross borders multiple times before the final car reaches a dealership.
That creates a basic problem:
If the tariff protects the finished vehicle but makes the parts more expensive, the factory may be protected on one side and squeezed on the other.
The automaker then has several choices:
- Raise prices.
- Accept lower profit margins.
- Delay investment.
- Shift production between plants.
- Reduce overtime.
- Slow hiring.
- Pass costs to suppliers and workers.
None of those choices requires a hiring boom.
Research from the Yale Budget Lab estimated that a 25% auto tariff could raise motor-vehicle prices substantially. J.P. Morgan estimated that tariffs on vehicles and parts could add thousands of dollars to the average vehicle’s cost over time, according to its analysis of auto tariffs.
The regular-guy translation is straightforward: if it costs more to build every car, the company needs to sell the car for more money or find savings somewhere else.
Hiring is one of the easiest savings levers to pull because a new worker is not just a wage. The cost also includes benefits, training, equipment, payroll taxes, safety compliance, and the risk that demand weakens before the new employee becomes productive.
What actually happened inside the factories?
The factories did not shut down across the country. Nor did tariffs have no effect whatsoever. Reality, as usual, refused to behave like a campaign slogan.
Some manufacturers increased domestic investment to reduce exposure to tariffs. Others delayed projects, changed production plans, paused lines, or canceled previously planned investments. The Congressional Research Service describes this mixed response: tariffs encouraged some U.S. investment while causing other projects to be reconsidered or abandoned.
Stellantis, for example, paused production of several vehicles made in Canada and Mexico. That disruption affected U.S. component plants and led to layoffs involving nearly 1,000 workers at five facilities, according to reporting compiled by Cars.com.
Volvo also announced workforce reductions, citing changing trade policies along with softer electric-vehicle demand. These examples illustrate the messy middle: a tariff can make domestic production more attractive in one location while making the entire production network less efficient.
A company may respond by adding a few jobs at a new American facility: but cutting jobs somewhere else, reducing shifts, or putting a different expansion on ice.
That is not reshoring as a clean victory parade. It is corporate triage.
The silver lining is real: but smaller than the sales pitch
There is a more favorable part of the data.
Manufacturing dismissals reached their lowest level in more than five years, while manufacturing vacancies climbed to their highest level since December 2023. That suggests factories were not conducting a massive wave of firings. Some employers still wanted workers, particularly for skilled positions, even while total new postings across the tracked automotive companies declined.
But a vacancy is not a job.
A vacancy is an open chair. It does not tell us whether the company can find someone qualified, whether the position is permanent, whether the wage is competitive, or whether the job will still exist after the next production adjustment.
This distinction matters. A factory can have unfilled openings and still avoid broad hiring because it cannot find workers with the right skills. It can also be short of electricians, maintenance technicians, robotics specialists, and machinists while cutting administrative roles or production positions elsewhere.
That is not necessarily a contradiction. It is a labor-market mismatch.
The United States has a shortage of some industrial skills, but that does not mean every laid-off worker can immediately step into an advanced manufacturing job. Modern auto plants use more robotics, software, sensors, and automated quality systems than the factories of previous generations.
The factory floor may need fewer people overall: but more specialized people.

Automation is the elephant: or perhaps the robot: in the factory
The debate over tariffs often assumes that the number of factory jobs depends mostly on where production occurs.
It does not.
It also depends on how production occurs.
An American factory built today is likely to be more automated than an American factory built 30 or 50 years ago. Robots do not call in sick, require health insurance, or ask for overtime. They also do not buy lunch at the local diner, which is bad news for the diner but excellent news for the factory’s productivity numbers.
This is why manufacturing output and manufacturing employment can move in opposite directions. A plant can produce more vehicles with fewer workers if it invests heavily in automation and process improvements.
That does not make the investment useless. Higher productivity can support better wages, stronger businesses, and more competitive factories. But it does mean that “more production in America” does not automatically translate into “millions of new factory jobs.”
The WardsAuto analysis of future auto jobs and tariffs makes this broader point: automation and technological change matter enormously in determining manufacturing employment.
Tariffs cannot repeal productivity.
The consumer pays while the worker waits
There is another uncomfortable part of the tariff story. The cost can arrive immediately, while the promised jobs may never arrive.
Higher prices show up in vehicles, replacement parts, appliances, and equipment. Businesses pay more for inputs. Consumers pay more at dealerships. Suppliers face narrower margins. Manufacturers become cautious.
Meanwhile, the job gains are conditional:
- The company must decide to build or expand domestically.
- The project must be large enough to require many workers.
- The investment must survive changing demand.
- Retaliatory tariffs must not damage exports.
- Automation must not eliminate much of the expected headcount.
- The new jobs must be located where workers can actually take them.
That is a lot of “ifs” attached to a policy marketed as a certainty.
The Kansas City Federal Reserve found that sectors more exposed to tariffs experienced slower job growth. Its analysis estimated that the economy could have added roughly 19,000 more jobs per month, on average, during part of 2025 without the direct tariff effects.
The estimate is not a perfect measurement of every factory, but it points in the same direction as the auto-posting data: tariffs created economic friction rather than a clean hiring surge.
What would bring factory jobs back?
If the goal is more American manufacturing employment, tariffs may be one tool: but they are a blunt one.
A serious industrial strategy would also address:
- Reliable and affordable energy
- Faster permitting for factories and infrastructure
- Better technical education and apprenticeships
- Childcare and transportation for workers
- Stable tax and trade rules
- Research and development
- Domestic production of critical components
- Access to affordable capital
- Stronger demand for American-made goods
Most importantly, policy must distinguish between manufacturing output and manufacturing employment. They are related, but they are not identical.
A country can make more things with fewer people. That is not a failure of arithmetic. It is what productivity looks like.
The 2025 auto tariffs may have shifted a few decisions, protected a few suppliers, and encouraged some domestic investment. But the evidence does not show the promised hiring boom. New U.S. postings among 18 automakers and suppliers fell roughly 8%, while factories navigated higher costs, supply-chain uncertainty, automation, and changing consumer demand.
Protection can change the map of production. It cannot guarantee the number of people standing on the factory floor.
For workers, that distinction is not academic. It is the difference between a headline and a paycheck.
Disclosure: Regular Guy Economics is not a financial advisor. This article is for educational and informational purposes only and is not investment advice.
Be mindful, be watchful and good luck.