

October 14, 2026
For tens of millions of households, Social Security is not a bonus or a side income. It is the steady deposit that helps cover groceries, utilities, housing and prescriptions. So when people hear “COLA,” they want to know one thing: How much more money will actually be in the monthly budget?
COLA stands for cost-of-living adjustment. The 2027 adjustment is tied to the inflation data released today, October 14, at 8:30 a.m. Eastern. The Senior Citizens League’s latest forecast before the September data came out was 3.5%. Its earlier estimate was 3.6%. A useful reminder that forecasts are not the official number. The September figures complete the calculation; the final COLA should be confirmed through the Social Security Administration.
Here’s how the system works, what a raise of that size could mean in dollars, and why the amount that appears on the announcement may not be the amount Grandma gets to spend.
COLA math uses a particular inflation gauge
The Social Security COLA is based on the Consumer Price Index for Urban Wage Earners and Clerical Workers, or CPI-W. That is not the broader headline CPI figure most people see in news coverage. It is a specific index, intended to track price changes for a defined group of workers.
The calculation uses the average CPI-W for July, August and September, the third quarter of the year, and compares it with the average for those same months the year before. If the average has increased, benefits are adjusted by the percentage change, rounded to the nearest tenth of a percentage point.
Think of it like comparing two three-month grocery receipts. The government does not take only September’s price change, or simply use the annual inflation headline. It checks the three-month average against the prior year’s three-month average. That’s why the final September CPI-W figure matters: it finishes the quarter and completes the comparison.
The Bureau of Labor Statistics’ CPI release provides the underlying data. Once the September figures are in, the arithmetic can be finished and the official COLA determined.
What might a 3.6% adjustment look like?
Percentages are tidy. Household budgets are not. Let’s translate the earlier 3.6% forecast into dollars using a round-number example.
If a retired worker receives $2,000 a month, a 3.6% increase would add about $72 per month, or $864 over a full year before any deductions. That’s the kind of raise that can help with a grocery run, part of a utility bill, or a recurring prescription cost.
If the final COLA were 3.5% instead, the same $2,000 benefit would rise by about $70 a month, or $840 a year. The difference between those two estimates is only about $2 per month on a $2,000 check. But the example also shows why it’s important to label projections correctly: neither estimate should be mistaken for the official rate.
Your household’s actual increase depends on your current benefit and the final COLA. A person receiving more than $2,000 would generally see a larger dollar increase than someone receiving less, because the adjustment is a percentage of the benefit. It is not a flat payment of $72 for everyone.

The raise on paper and the deposit in the bank can differ
Here’s the catch that can make the October announcement feel bigger than the check that arrives later: many beneficiaries have Medicare Part B premiums deducted directly from their Social Security payments.
Part B helps pay for doctor visits, outpatient care and other services. Its monthly premium is set separately from the Social Security COLA. If that premium rises, it takes a larger bite out of the benefit before the deposit reaches the bank account.
For a simplified example, suppose a person’s benefit goes up by $72 a month, but the amount deducted for Part B also rises. The person’s net deposit, the money actually available for bills, would increase by less than $72. The COLA is still applied to the benefit, but the deduction affects the spendable amount.
The Part B premium is typically announced later in the fall, often in mid-November. So October brings the COLA news, but the full picture of the next year’s net deposit may not be clear until the Medicare premium is announced. The Centers for Medicare & Medicaid Services publishes official Medicare premium information.
There is a safeguard called the hold harmless provision. In general, it protects eligible people whose Part B premiums are deducted from their Social Security benefits from having their net Social Security payment reduced below the previous year’s level solely because of an increase in the standard Part B premium. But it does not protect everyone or guarantee that every person keeps the full COLA as extra spending money. Some people, including certain new beneficiaries and those paying higher income-related premiums, may not qualify. The Social Security Administration explains how the provision works.

A COLA looks backward
The COLA is meant to help benefits keep up with inflation, but it is based on price changes that have already happened. The adjustment arriving in 2027 reflects the CPI-W change over the third quarter of 2026 compared with the third quarter of 2025. It cannot tell us what grocery prices, energy bills or rent will do next year.
That timing matters for a household living on a fixed monthly income. Prices do not wait for the next adjustment. A winter heating bill can climb in January; the grocery total can rise at any point during the year. By the time a COLA responds, the household has already been absorbing those costs.
There is another wrinkle: CPI-W tracks a group of urban wage earners and clerical workers, not a typical retiree’s personal budget. Older households may spend a different share of their income on medical care, utilities and food. Even if the index rises by a certain percentage, that does not mean every household’s expenses rose by precisely the same amount.
The inflation people feel is personal
Energy and food costs are especially visible because they show up in regular, unavoidable purchases: heating a home, filling a prescription, buying milk and bread. Those costs can weigh heavily on older adults, particularly people who spend a large portion of their monthly income on essentials.
An average index can be useful for measuring a broad trend. It cannot describe every kitchen table. One household may feel the squeeze most in electricity and heating; another may be hit by rent, transportation or medication. A COLA offers a broad adjustment, but it is not a custom reimbursement for each person’s actual bills.

That is why the best way to read the announcement is in two steps. First, find the official COLA percentage, not an earlier forecast. Then calculate what it means for the actual benefit, and wait for the Part B premium announcement before assuming that the entire increase will show up in the bank account.
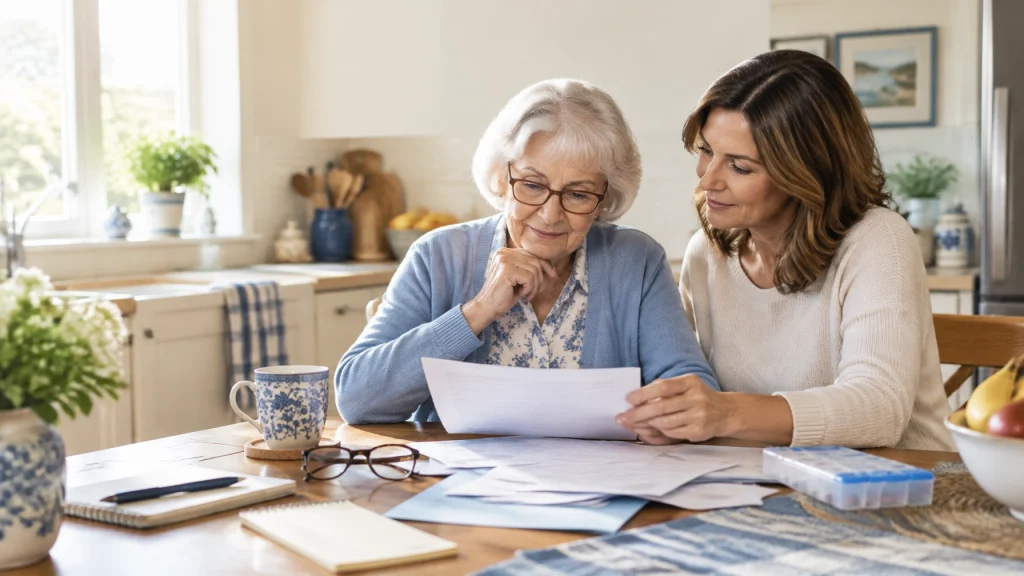
A few practical steps can help: check the benefit amount on the Social Security statement, note whether Medicare premiums are deducted, and review the net deposit once the new benefit and premium take effect. If a parent or grandparent relies on that deposit to cover household bills, walking through the arithmetic together can make the announcement less confusing, and help prevent an estimate from being mistaken for money already in hand.
Be mindful, be watchful and good luck.
This article is for educational purposes only, is not investment advice, and should not be treated as personalized financial, tax, legal or benefits advice. Social Security and Medicare rules can depend on individual circumstances. Talk with a qualified professional or contact the Social Security Administration or Medicare for help with your situation.