

November 10, 2026
The economy grew at a 3.4% annualized rate in the third quarter. That is a strong quarter by ordinary historical standards. Yet employers added just 29,000 jobs in September, unemployment rose to 4.2%, and average hourly earnings increased by only 0.1% for the month.
Those numbers seem like they came from different economies. Usually, when businesses produce more, they need more workers. This time, growth and hiring are moving to different rhythms.
That does not mean the growth number is fake, or that one weak jobs report proves the economy is in trouble. It means the kind of growth matters, and the headline GDP number does not tell the whole kitchen-table story.
GDP counts production. Payrolls count people.
GDP measures the value of goods and services produced across the economy. Payrolls count people employed by businesses and government. They are related, but they are not the same measure.
When demand rises, companies often need more staff to make and sell more things. That is the familiar connection between growth and jobs. But businesses can also grow by investing heavily in equipment, software, buildings, and technology. Things that can increase output without requiring a matching number of permanent employees.
The Bureau of Economic Analysis’s Q3 estimate says growth accelerated from 2.2% in the second quarter to 3.4% in the third. Investment, consumer spending, and government spending contributed. The BEA also reported that real final sales to private domestic purchasers, a measure combining consumer spending and private fixed investment, rose 4.9%.
That is real activity. But it does not mean every employer is opening a new shift or adding a row of desks.
1. A growing share of growth is capital-heavy
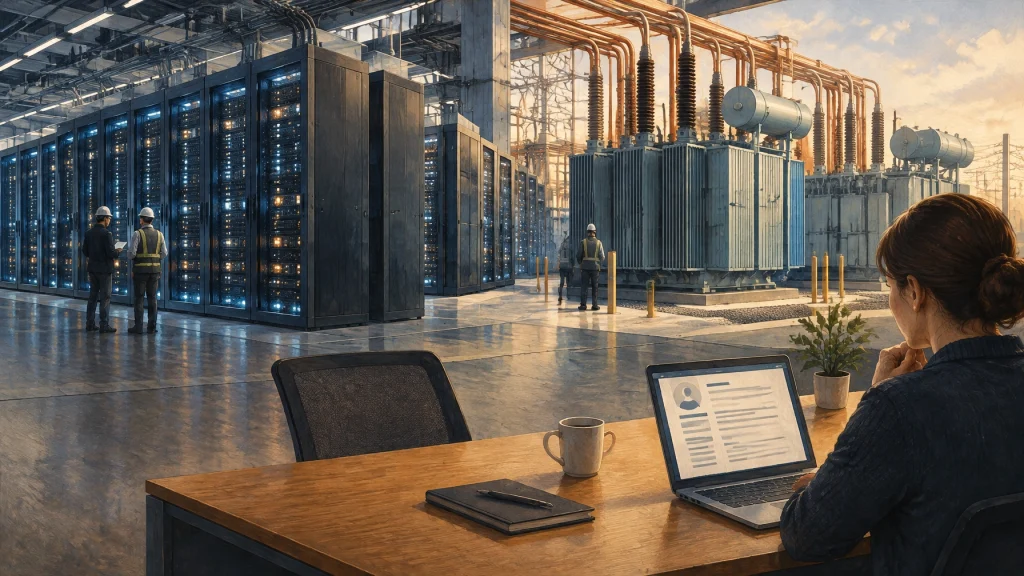
A significant part of today’s investment story is tied to AI: servers, data centers, chips, and the power infrastructure needed to run them. A data center can require enormous spending on land, buildings, cooling systems, electrical equipment, and computing hardware. Once it is operating, it may need relatively few permanent employees compared with a large factory, store network, or service business employing thousands.
A billion dollars spent on a chip plant or a data center can add substantial economic activity, but it does not automatically create as many jobs as a billion dollars invested in a labor-intensive business. GDP records the economic output and investment. Payrolls register the workers. Different inputs, different scoreboard.
Regular Guy Economics’ estimate is that growth outside the AI-related boom is running at about 1%. That is an analytical estimate, not an official BEA statistic: the government does not publish an “ex-AI GDP” series, and AI-related activity is difficult to separate cleanly from other investment. Still, the distinction helps explain how the headline can look lively while much of the labor-employing economy feels barely in motion.
The simplest translation: the country can be building a lot of expensive infrastructure without creating a lot of new career openings.

2. Employers are holding on to workers, and holding off on hiring
The labor market can cool without a wave of layoffs. That is the strange middle ground businesses appear to be occupying: they are not rushing to cut existing staff, but they are cautious about adding new people.
Initial jobless claims have been around 197,000, a relatively low level, while September payroll growth was only 29,000. Low layoffs alongside weak hiring is not a booming job market. It is a frozen one.
Why freeze? Hiring is a commitment. A new employee means wages, training, benefits, and the risk that the position will still be needed if business conditions change. Tariff uncertainty, war-related costs, and interest rates can make companies more reluctant to add staff, even when they are still investing and producing.
Workers are also quitting less often. A low quits rate usually means people are less confident they can leave one job and quickly land a better one. That caution may make it easier for employers to retain current workers, but it also leaves job seekers competing for fewer openings. A person with a job may feel secure enough to stay put; someone without one may find the door barely open.
3. A smaller labor force can make the unemployment rate misleading
Unemployment is not a simple count of everyone without a job. To be counted as unemployed, a person generally needs to be actively looking for work. If people stop searching, they leave the labor force, and they are no longer included in the unemployment-rate calculation.
That matters when participation is weak. In July, the labor force contracted by 264,000, and the participation rate fell to 61.4%, its lowest level since 2021. By September, participation had recovered to 61.8%, according to the Bureau of Labor Statistics. The monthly figures move around, so it is important not to treat July’s 61.4% as September’s current reading. But the broader point remains: participation and the number of people looking for work can change the story behind the unemployment rate.
If fewer people are actively searching, unemployment can hold steady, or even fall, without employers hiring much. That is why 4.2% unemployment does not, by itself, settle whether finding a job feels easy.
The wage number says plenty
Average hourly earnings rose 0.1% in September. That is essentially flat for the month. Over the year, average hourly earnings were up 3.0%.
Headline PCE inflation, meanwhile, was 3.6% year over year. These are not perfectly matched measures. One tracks average hourly earnings, the other a broad basket of consumer spending, and a one-month wage change should not be compared directly with a twelve-month inflation rate. But the annual comparison is still a useful rough check: if wages are rising more slowly than prices, the paycheck buys a little less.
That is the household version of the frozen labor market. When employers are competing hard for workers, they tend to offer higher pay. When hiring is stalled and workers are staying put, that pressure weakens. A 0.1% monthly raise is not much help at the checkout counter.
The October jobs report is the next test
The October Employment Situation was scheduled for Friday, November 6. By the time this article is read, the report may already be available. Either way, it is the next important test of whether September’s weak hiring was a one-month stumble or part of a longer slowdown.
Start with payroll growth, of course, but do not stop there. Look at revisions to September and August. The BLS cut those two months by a combined 60,000 in its September report. Revisions are normal as more employer information arrives, but a pattern of downward adjustments can show that the first headline was rosier than the underlying trend.
Next, check participation. If the labor force shrinks, unemployment can remain at 4.2% even while hiring is scant. Finally, check average hourly earnings. Monthly wage growth below 0.3% would be another sign that employers are not competing aggressively for workers. One month is not a verdict, but several weak readings begin to look like a pattern.
The BLS release calendar lays out the publication schedule. The report itself is a better guide to the labor market than guesses made before it lands.
The kitchen-table translation
There is a reason economic confidence can look grim even when GDP is growing. A recent consumer-sentiment reading of 46.3 points to a public that feels uneasy. That can be true at the same time as a 3.4% GDP reading.
GDP tells us the economy produced more. It does not tell every household that work is easier to find, raises are generous, or next month’s bills are manageable. This expansion is real, but a lot of its energy is going into infrastructure and equipment, not necessarily into new jobs and careers.
The regular person experiences the economy through the hiring market, the paycheck, and the grocery bill. If jobs are scarce and wages are barely moving, a strong GDP headline can feel like good news happening somewhere else.
For more plain-English economic context, explore Regular Guy Economics.
Be mindful, be watchful and good luck.
This article is for educational purposes only and is not investment advice. Economic data can change as estimates are revised. Talk with a qualified financial professional before making investment or other financial decisions.