

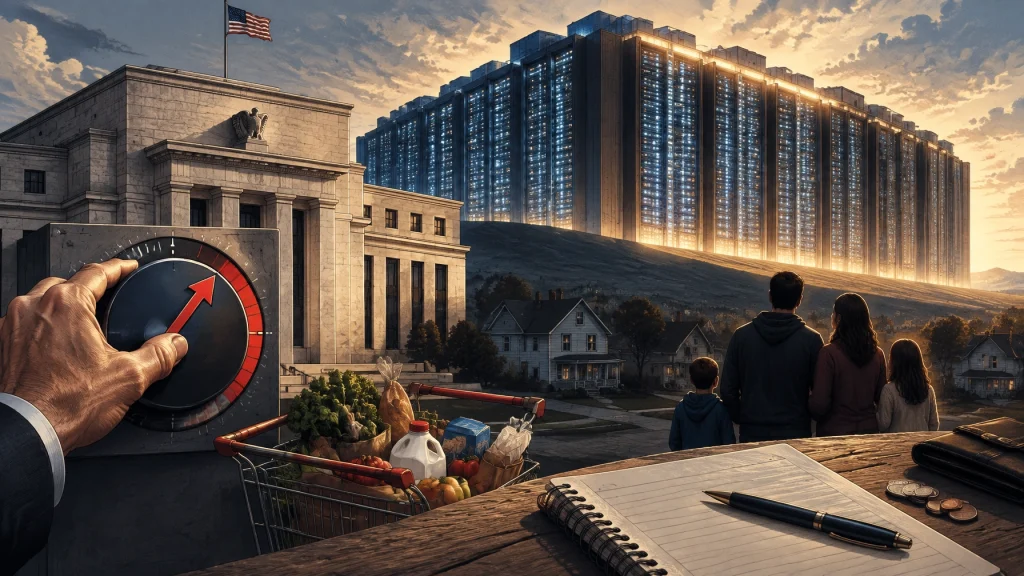
The Federal Reserve raised interest rates on September 16, and the official explanation was familiar: the economy is expanding at a solid pace, domestic spending is resilient, productivity is strong, and capital investment is robust.
That is the Fed’s case for taking away the punch bowl.
The Federal Open Market Committee voted unanimously to raise the federal funds rate by a quarter point, moving the target range to 3.75%–4.00%. Banks responded by lifting the prime rate to roughly 7.00%. The Fed says the move will support a “timelier” return to its 2% inflation goal, and its projections suggest at least one more increase before the end of the year.
The official statement is available from the Federal Reserve.
There is only one problem with the “strong economy” argument: a meaningful portion of the strength appears to be concentrated in artificial intelligence and the infrastructure required to build it.
Strip out the AI-related capital spending, and U.S. growth so far in 2026 looks closer to 1% annualized, not 2%.
That is not a collapse. But it is getting close to stall speed. And it raises an important kitchen-table question:
When the Fed says the economy can absorb higher rates, which economy is it talking about?
The headline economy is slowing
Real GDP grew at a 1.5% annual rate in the second quarter of 2026, down from 2.1% in the first quarter. The full-year growth rate for 2025 was also 2.1%.
On the surface, those numbers look respectable. They are not recession numbers. They are not boom numbers either.
The economy is moving forward, but not particularly quickly. Much of the apparent strength is coming from consumer spending and business investment in technology. Other parts of the economy are contributing less, or actively pulling in the opposite direction.
In the second quarter:
- Consumer spending contributed 2.3 percentage points to GDP growth.
- Nonresidential fixed investment contributed 1.2 percentage points.
- Inventories subtracted 0.7 percentage points.
- Net exports subtracted 1.1 percentage points.
- Government spending subtracted 0.2 percentage points.
That is an economy being carried by consumers and investment, while trade, inventories, and government activity drag on the other side of the scale.
The Bureau of Economic Analysis GDP data provides the official breakdown. The simple translation is that the economy is not broad-based and balanced. It is being propped up by a few powerful engines.
One of those engines is AI.

AI is doing a lot of the lifting
In the first quarter, computer investment grew at a stunning 67.4% annualized rate. Software investment grew 22.6%.
Those two categories contributed approximately:
- 0.58 percentage points from computer investment
- 0.51 percentage points from software
That is about 1.09 percentage points combined.
Q1 real GDP grew at a 2.1% annual rate. In other words, computers and software accounted for more than half of the quarter’s total growth.
That does not mean every bit of computer investment was AI. A company buying ordinary office equipment is not automatically building ChatGPT. But the timing, scale, and concentration of the spending make the relationship hard to ignore. Data centers, chips, servers, networking equipment, cooling systems, and software are all being purchased at extraordinary rates because the market believes AI infrastructure will generate extraordinary returns.
For the second quarter, ING’s analysis offers several ways to measure the technology contribution.
A broad measure of technology investment accounts for roughly 50% of year-over-year GDP growth. Narrow the definition to computers, peripherals, and software, and the figure is about 44%.
Then subtract the imported computers, peripherals, and semiconductors. That matters because spending money on an imported server does not create the same amount of domestic value as building the server, designing the chip, or providing the service inside the United States.
After that adjustment, ING estimates that technology investment accounted for approximately 36% of year-over-year GDP growth in the second quarter, roughly one-third of the total.
The full ING analysis is available here.
That is the more conservative estimate. Other estimates put AI-related activity at as much as 75% of first-quarter growth, depending on what gets counted and how the calculation is made.
The exact number is debatable. The concentration is not.
What happens when the servers are removed?
Using the central estimate, the arithmetic is straightforward:
- Q1 headline growth: 2.1%
- Estimated AI contribution: approximately 1.1 percentage points
- Q1 growth without AI: roughly 1.0%
For Q2:
- Q2 headline growth: 1.5%
- Estimated AI contribution: approximately 0.5 percentage points
- Q2 growth without AI: roughly 1.0%
Taken together, first-half 2026 growth comes in around 1.8% annualized on the headline number. Without the estimated AI contribution, the economy is growing at approximately 1% annualized.
That is the central estimate, not a laboratory measurement. There is no official GDP line labeled “AI.” The government does not publish a box that says, “This quarter’s growth from server farms: 0.51 percentage points.”
Still, the estimate is useful because it asks the question that headline GDP does not:
How much of the economy is growing without the AI buildout?
The answer appears to be: not very fast.
The one-industry economy
This is the same issue raised in Regular Guy Economics’ two-part series, “The Fantasy of the AI Marketplace.” The same seven companies driving the stock market are also driving a large share of the investment story and, increasingly, the GDP story.
That is a concentration problem.
A healthy economy has many engines: housing, manufacturing, small business, services, exports, household income, construction, and government infrastructure. When one sector becomes responsible for an unusually large portion of investment and market gains, the economy becomes a single-engine aircraft flying through a storm.
The AI engine is powerful. It is also expensive, concentrated, and dependent on continued borrowing, rising electricity supply, favorable financing, and the belief that future profits will justify today’s spending.
Meanwhile, non-tech capital spending has been weak. Nonresidential investment outside the technology boom has fallen year over year for six straight quarters through the first quarter of 2026. That suggests AI spending may not simply be adding to total investment. It may be crowding out other projects.
Capital is not infinite. A dollar directed toward a giant data center is a dollar that may not be directed toward a factory, a regional hospital, a small-business expansion, or an ordinary office building.
Inflation makes the growth look better than it feels
There is another problem with relying on consumer spending.
Consumer spending contributed 2.3 percentage points to Q2 GDP growth, but the PCE price index rose at a 5.3% annualized rate. Core PCE inflation rose 3.6%.
That means households were spending, but prices were eating a meaningful portion of the benefit.
A family spending more at the grocery store is not necessarily becoming wealthier. A household paying more for insurance, rent, utilities, and medical care is not experiencing a boom just because the spending appears in GDP.
This is why the Fed is hiking. It is not primarily raising rates because it wants to punish AI companies or because 1.5% GDP growth is dangerously strong. It is raising rates because inflation remains too high and has lasted too long.
The concern is that elevated prices become embedded in wages, rents, contracts, services, and expectations. A temporary price increase becomes a permanent new starting point.
That is the second-order effect.

The regular guy pays for the boom
The AI buildout also connects to the earlier Regular Guy Economics post, “Your Electric Bill and the Data Center Down the Road.”
A data center can create construction jobs, equipment orders, tax revenue, and GDP growth. But the costs do not vanish. Somebody has to supply the electricity, build the transmission lines, expand the grid, provide water for cooling, and finance the project.
Those costs eventually appear somewhere:
- Higher utility bills
- More expensive power infrastructure
- Pressure on local water systems
- Higher rents near construction corridors
- Public subsidies and tax incentives
- Greater demand for debt and financing
GDP records activity. It does not automatically tell households whether that activity improved their lives.
A billion-dollar server farm counts as investment. A family paying more for electricity to support the server farm experiences it as a bill.
That distinction matters when policymakers look at the headline numbers and decide the country can handle higher interest rates.
What should the Fed be watching?
The Fed is right to take inflation seriously. Five-percent price growth is not compatible with stable household finances, even if the unemployment rate remains low and technology companies are spending aggressively.
But the Fed should also be careful about confusing concentrated investment with broad economic strength.
If one-third to one-half of growth is tied to one industry building server farms, then monetary policy is being set based partly on the health of a single sector. Higher rates may not stop AI companies from spending if they have enormous cash balances and stock-market support. They may, however, hit housing, small businesses, consumers with credit-card balances, and companies that lack access to cheap capital.
That is the danger of steering the entire economy by looking at one very bright dashboard light.
The broader economy may be growing, but at roughly 1% without AI. That is not a recession. It is not a sturdy expansion either.
It is a narrow bridge.

The honest conclusion
The Fed’s September hike makes sense if inflation is still running hot. The mistake would be assuming that strong AI investment proves the entire American economy is equally healthy.
The data tell a more complicated story:
- GDP growth slowed from 2.1% in Q1 to 1.5% in Q2.
- Computer investment surged 67.4%.
- Software investment rose 22.6%.
- AI-related technology investment may account for roughly one-third of current growth, or substantially more under broader definitions.
- Consumer spending is carrying the economy while inflation reduces its real purchasing power.
- Non-tech investment is weak.
- Without AI-related capital spending, first-half growth appears closer to 1% annualized.
The caveat is important: AI’s indirect effects cannot be cleanly removed. Rising stock prices can make wealthy households spend more. AI may improve productivity in industries that do not show up neatly in a technology category. Imported equipment still supports domestic construction, installation, and services.
So the 1% figure is a central estimate, not a precise fact carved into stone.
But the question remains valid. When the Fed says the economy is resilient enough to absorb another rate hike, ask what economy it is looking at.
Because if the answer is mostly seven companies, a mountain of borrowed money, and a forest of server farms, then the country may not have a broad-based boom.
It may have one industry wearing a costume.
This article is for educational and informational purposes only. It is not investment advice. Before making financial decisions, readers should consult a qualified financial professional.
Be mindful, be watchful and good luck.