

September 18, 2026
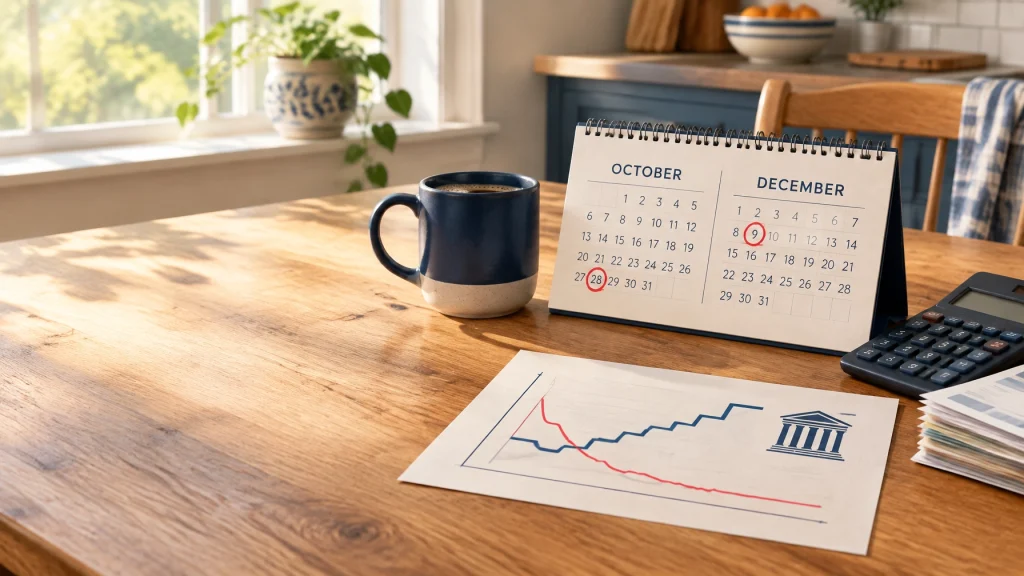
Put these two dates on the fridge: October 28 and December 9.
Those are the next Federal Open Market Committee meetings, and the Federal Reserve has already made clear that the rate-hike story may not be finished for 2026. After raising the federal funds target range to 3.75%–4.00% on September 16, the Fed’s own projections point toward at least one more increase before the year ends.
The October decision is close to a coin flip. Markets are roughly divided between a hold and another quarter-point hike. December is the backup date if the Fed decides to wait for more information.
This is not a reason to panic, cancel Christmas, or bury cash in the backyard. It is a reason to know which numbers matter and make a few practical decisions before the next headline arrives.
Disclosure: Regular Guy Economics is not a financial advisor. This article is for general education and planning purposes only. It is not investment advice or a personalized recommendation.
The simple version: the Fed is waiting for proof
The Fed wants inflation to move back toward its 2% target, but the latest projections show that road is still bumpy.
The September projections put:
- 2026 headline PCE inflation at 3.7%
- 2026 core PCE inflation at 3.4%
- 2026 unemployment at 4.1%
- The median year-end federal funds rate at about 4.1%
The Fed does not officially target the Consumer Price Index, or CPI. It targets the Personal Consumption Expenditures price index, known as PCE. But CPI remains the inflation report most households recognize because it tracks familiar expenses such as food, gasoline, rent, utilities, and clothing.
The practical point is simple: inflation is still running well above the Fed’s comfort zone. The September rate increase was not supposed to solve the problem overnight. It was a signal that policymakers believe rates may need to remain higher for longer.
According to the Fed’s projections, 16 of 18 participants see at least one additional hike this year. Four see the possibility of two more. That is not a promise. The dot plot is a collection of individual forecasts, not a binding contract signed in red ink. But it tells us where the committee’s thinking is pointed today.
The direction can change quickly if the data changes.
The October 28 meeting: watch three things

1. CPI: are prices still accelerating?
The mid-month CPI report will be one of the most important pieces of information before October 28.
The Fed will pay particular attention to core inflation, which removes food and energy from the headline number. That may sound strange when gasoline is eating the family budget, but the reason is that food and energy can swing sharply from month to month.
Policymakers want to know whether price increases are spreading into the rest of the economy. Are rents still climbing? Are services getting more expensive? Are businesses passing higher wages and input costs along to customers?
A single hot month will not automatically guarantee a hike. But a pattern of stubborn core inflation makes a quarter-point increase more likely.
A cooler CPI reading would do the opposite. If inflation is clearly slowing, the Fed can afford to wait and see whether previous rate increases are finally working their way through the economy.
2. The jobs report: strong enough to keep spending alive?
The employment report arrives on the first Friday of the month. For the October meeting, that means the early October jobs report will be central to the conversation.
The Fed has two responsibilities: price stability and maximum employment. It does not want to crush the labor market simply to bring down prices. But a strong labor market can keep inflation alive because employed people continue spending, businesses keep hiring, and wages can support higher prices.
The September projections put the unemployment rate at 4.1% for 2026, lower than the Fed’s previous estimate. That suggests policymakers do not currently see an economy falling off a cliff.
A strong jobs report, especially one showing solid payroll growth and persistent wage pressure, could push the Fed toward another hike. A weak report could make officials more cautious.
The key is not one magic payroll number. The Fed will look at the trend: hiring, unemployment, wage growth, hours worked, and whether job openings are drying up.
3. Oil: the wild card nobody can schedule
Oil prices are the least predictable part of this story.
If crude remains near $100 a barrel, the effects spread beyond the gas pump. Transportation gets more expensive. Airlines face higher fuel costs. Trucking and shipping costs rise. Grocery distributors pay more to move food, and businesses eventually try to pass those costs to customers.
The Fed cannot pump more oil, reopen a shipping lane, or negotiate a ceasefire. It cannot directly control the price of energy.
What it can do is prevent an oil shock from becoming a permanent inflation habit. If businesses and workers begin assuming that prices will keep rising, they may raise prices and wages accordingly. That is the second-round effect the Fed worries about.
There is also an important caveat: a resolution involving the Strait of Hormuz could push oil prices lower. If that happened, some of the pressure behind another hike could disappear entirely. A meaningful decline in oil would make it easier for the Fed to hold rates steady in October.
That is why forecasting a Fed meeting by staring at one number is a fool’s errand. The committee will be looking at the entire dashboard.
Before October 28: the practical checklist

The October meeting is close enough that floating rates deserve attention now.
Lock in a floating rate if the deal makes sense
If you are shopping for an auto loan, refinancing a variable-rate debt, or using a home equity line of credit, ask whether the rate is fixed or floating.
A quarter-point Fed hike does not always pass through to every loan immediately or in exactly the same amount. But variable-rate borrowing generally feels changes faster than fixed-rate borrowing.
Get the terms in writing. Compare the total cost, not just the advertised rate. A slightly lower rate with expensive fees can be a financial costume party: it looks good until the bill arrives.
Consider a CD ladder
Certificates of deposit with yields near 4.5% may be worth considering for money you do not need immediately.
A CD ladder means dividing cash among several maturity dates instead of locking everything away at once. For example, someone might use three-, six-, nine-, and twelve-month CDs. As each CD matures, the money can be spent, renewed, or moved if rates change.
The advantage is flexibility. The disadvantage is that early withdrawals may trigger penalties, and no bank product should replace money needed for immediate emergencies.
Make sure the emergency fund is earning something
An emergency fund belongs somewhere safe and accessible, but “accessible” does not have to mean “earning 0.01%.”
Check whether your cash is sitting in a basic checking account while your bank offers a higher-yield savings option. Compare the annual percentage yield, fees, withdrawal rules, and deposit insurance coverage.
The objective is not to chase every tiny rate difference. The objective is to stop paying an invisible penalty for leaving your cash unattended.
Between the meetings: do not build your life around a forecast
After October 28, rates may rise, stay put, or markets may immediately begin guessing about the December meeting. That is when many people make the mistake of treating a forecast like a command.
Do not delay a necessary financial decision solely because someone on television predicts a rate cut next year. Do not rush into a loan solely because someone else predicts rates will rise forever.
Instead, ask:
- Can the monthly payment fit comfortably in the budget?
- Is the rate fixed or variable?
- Are there fees, penalties, or prepayment restrictions?
- How much cash must remain available?
- What happens if the rate is 1% higher than expected?
That last question is the grown-up question. Plans should survive ordinary disappointment.
Before December 9: the holiday-season checklist

December arrives with decorations, travel, gifts, and a remarkable ability to turn a manageable credit-card balance into a small personal recession.
Reassess card debt before the shopping begins
Credit-card rates generally track the prime rate and can adjust quickly after a Fed move. Before holiday spending accelerates, check:
- Your current APR
- Your outstanding balance
- Your minimum payment
- The interest charged last month
- Whether a promotional balance-transfer offer is actually cheaper after fees
Paying down the highest-rate balance first is the avalanche approach. Paying the smallest balance first is the snowball approach. The mathematically superior method is usually the avalanche, but the method that keeps a person consistently paying down debt is the one that works in real life.
Either way, avoid adding new holiday debt while congratulating yourself for paying off the old balance.
Revisit your savings rate
If the Fed hikes again, savings accounts and short-term products may eventually pay a little more. The increase may not arrive immediately, and your bank may not pass along the full improvement.
Check the rate. Ask whether your account is competitive. Automate a transfer if your budget permits. Even a modest increase in the amount saved each month matters more than spending hours trying to predict the exact next Fed decision.
Review your 2027 borrowing plans
If you expect to buy a car, move, renovate, or refinance in 2027, use December to estimate the payment under several interest-rate scenarios.
The goal is not to guess the Fed perfectly. The goal is to know what your household can handle if borrowing costs remain elevated.
Put the dates on the fridge
Here is the calendar in plain English:
- Now through early October: Review floating-rate debt and where emergency cash is held.
- Early October: Watch the jobs report.
- Mid-October: Watch CPI, especially core services and shelter.
- Before October 28: Compare rate-lock options, review CD terms, and make sure savings are earning a reasonable return.
- After October 28: Do not overreact to the announcement. Check what actually changed in your accounts.
- Before December 9: Review credit-card debt, holiday spending, savings rates, and any major borrowing plans.
- After December 9: Recheck rates and update the household budget for 2027.
The Fed will keep talking in basis points, projections, and carefully polished sentences. Households can respond with something more useful: a calendar, a calculator, and a plan that does not require perfect predictions.
Be mindful, be watchful and good luck.