

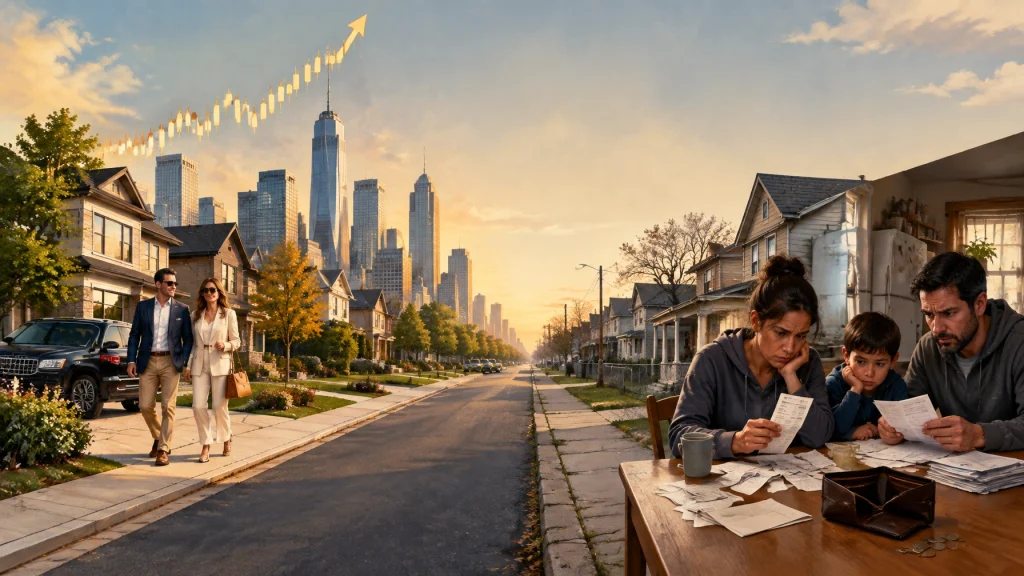
There is a sentence that drives ordinary people crazy:
“The economy is growing.”
That sentence may be perfectly accurate. It may also have almost nothing to do with whether your rent went up, your grocery bill got heavier, or your paycheck disappeared three days before payday.
Both things can be true.
The economy can be expanding while millions of households feel poorer. The stock market can be setting records while people are delaying dental work. Corporate earnings can look excellent while shoppers are timing their Walmart trips around their next direct deposit.
This is not a contradiction. It is a distribution problem.
It is also one of the most important ideas running through Douglas Murray’s The Strange Death of Europe: the people making policy often see the large picture, while the people living with the consequences experience something much more immediate and personal.
The spreadsheet says progress. The street says, “That’s nice. Who is paying for it?”
The 61% problem
A July 2026 CNBC All-America Economic Survey found that 61% of registered voters were pessimistic about both the current economy and its future.
That is a remarkable result because it arrived alongside a strong stock market and lower gas prices.
If the economy is supposedly doing well, why do so many people feel so bad?
The easy answer is that people are uninformed. The more useful answer is that people are looking at a different set of numbers.
Economists and financial commentators tend to watch:
- GDP growth
- Corporate profits
- Stock-market indexes
- Unemployment
- Productivity
- Business investment
Households watch:
- Rent or mortgage payments
- Grocery receipts
- Insurance premiums
- Credit-card balances
- Medical bills
- Car repairs
- Whether the paycheck lasts until Friday
The first list describes national activity. The second describes household survival.
Both lists matter. But they are not the same thing.

The millionaire paradox
The United States now has approximately 23.6 million dollar millionaires, according to the UBS Global Wealth Report 2026.
That number tells us something real: America has created extraordinary wealth.
It does not tell us that most Americans feel wealthy.
A millionaire count is heavily influenced by home prices, stock portfolios, business ownership, and other assets. If somebody bought a house for $250,000 and it is now worth $800,000, that person may be a millionaire on paper without having an extra $550,000 sitting in a checking account.
Meanwhile, the person renting that same house may be paying much more every month without receiving any of the benefit from the appreciation.
This is how the country can produce more millionaires while a large share of the population feels financially cornered. Wealth is rising, but ownership of that wealth is not evenly distributed.
The headline says prosperity. The household says, “The landlord raised the rent again.”
GDP is a total, not a report card for your family
Gross domestic product measures the total value of goods and services produced in the economy. It is useful. It is also blunt.
GDP does not tell us who received the income generated by that production.
Suppose ten people live in a town. Nine earn $50,000 a year. One earns $10 million. The average income for the town looks impressive. The median income, the income of the person in the middle, still looks like $50,000.
The average is pulled upward by the person at the top. The median tells us more about the typical household.
That distinction becomes more important as wealth and income become concentrated. A National Bureau of Economic Research analysis found that over one measured period, real per-capita GDP rose roughly 65%, while real median household income rose only about 11%.
That is the entire argument in one set of numbers.
The country produced more. The average became richer. The typical household did not receive a proportional share of the improvement.

Welcome to the K-shaped economy
The phrase “K-shaped economy” sounds like something invented by a committee that enjoys confusing people. It is actually fairly simple.
Imagine the letter K.
The upper arm moves upward. That represents households with valuable assets, strong incomes, secure employment, and meaningful exposure to the stock market. Their homes appreciate. Their retirement accounts grow. They can absorb higher prices because they have more room in the budget.
The lower arm moves downward. That represents households with little savings, limited assets, variable work, and large exposure to necessities. Their wages may rise, but rent, food, insurance, and healthcare rise faster.
The important point is that both arms exist at the same time.
The Richmond Fed and the New York Fed have both examined this widening divide.
A strong stock market is real. The wealth created for investors is real. The financial strain experienced by non-investors is also real.
A rising tide does not lift every boat if some households own yachts, some own rowboats, and some are standing in the water.
Walmart’s payday economy
Walmart provides a useful view of the economy from the parking lot.
The company’s financial results have been strong. Walmart reported fiscal 2026 revenue of $713.2 billion, and Walmart U.S. comparable sales rose 4.3%, according to its annual report.
That is the corporate version of the story.
The household version is more complicated.
Walmart executives have described lower-income shoppers as stretched and managing spending from paycheck to paycheck. Research has also found that shopping activity rises around paydays, when households have just received income and can restock the pantry.
That means Walmart can report strong earnings while many of its customers are still struggling. In fact, inflation and financial pressure may push more shoppers toward Walmart because they are searching harder for lower prices.
The store earns more. The customer may still feel poorer.
Those outcomes are not mutually exclusive.
Walmart has also attracted more middle- and higher-income shoppers looking for value. That helps explain why corporate earnings can stay healthy even while lower-income customers pull back. The company is benefiting from both financial stress and affluent bargain hunting.
One store. Several economies.
The benefits are diffuse. The costs are personal.
This is where Murray’s argument becomes portable beyond Europe.
An official in Brussels or London may look at a large economic picture and see:
- More workers
- Higher total GDP
- Lower-cost services
- More restaurant labor
- Population growth
- New business formation
Those benefits may be real. But the costs can land in a much more concentrated way.
A person on a particular street may see:
- Housing becoming more expensive
- More competition for entry-level jobs
- Public services under pressure
- A familiar neighborhood changing rapidly
- Wages failing to keep up with living costs
The benefits are spread across millions of transactions and may show up as slightly cheaper services or more available labor. The costs are visible every morning when a family searches for an apartment, competes for a job, or waits for a crowded public service.
This is why “the economy is growing” can sound insulting when somebody is worse off.
The statement may describe aggregate output. It does not answer the household question: “What happened to my share?”
The trust problem
Eventually, the argument stops being about economics and becomes a problem of trust.
When people hear that conditions are good but their own wallet says otherwise, they begin to distrust the messenger. If the response is, “You are wrong; the numbers say everything is fine,” the distance gets wider.
The numbers may not be wrong. The communication is incomplete.
People are not asking for every statistic to be negative. They are asking for someone to acknowledge that the gains are distributed unevenly and that transition costs are not imaginary.
This is the seed of the populist backlash across the West. It grows when elites describe a successful system that ordinary people do not recognize from their own block.
The solution is not to throw away GDP, stock prices, or corporate earnings. The solution is to stop treating those measures as a complete description of national wellbeing.
A serious economic conversation should include:
- Median household income
- Real wages after inflation
- Housing costs
- Healthcare and insurance expenses
- Household debt
- Wealth ownership
- Labor-force participation
- Regional differences
- The cost and availability of public services
That is the economic equivalent of looking under the hood instead of admiring the paint job.
The kitchen-table conclusion
If you feel worse off while the headlines celebrate growth, you are not necessarily confused. You may simply be living on the lower arm of the K.
The economy can grow because businesses sell more, profits rise, and asset prices climb. At the same time, your personal economy can shrink because necessities consume more of your paycheck and you own fewer appreciating assets.
The average can improve while the median struggles.
The country can become richer while your household becomes more fragile.
And a government can point to excellent national statistics while a specific street experiences very different results.
That is not madness. It is what happens when aggregate growth and shared prosperity drift apart.
The regular-guy test is simple: after the speeches, the GDP release, and the record close on the stock market, can an ordinary household pay the bills, save a little, handle an emergency, and believe tomorrow will be better?
Until the answer is yes for more people, “the economy is growing” will remain only half a sentence.
Disclosure: This article is for general informational and educational purposes only. Regular Guy Economics is not a financial advisor, and this content is not investment advice. Do your own research and consult a qualified professional before making financial decisions.
Sources: CNBC All-America Economic Survey, UBS Global Wealth Report 2026, Walmart 2026 Annual Report, Richmond Fed on the K-shaped economy, and New York Fed analysis.
Be mindful, be watchful and good luck.