

The housing market has reached the part of the cycle where everyone starts asking the same question:
Should you buy now, or wait for mortgage rates to fall?
The uncomfortable answer is that waiting may work. It may also leave you renting for another year while home prices rise, rates stay high, or the perfect house disappears. Nobody knows. The Federal Reserve does not know. The person shouting confidently on television almost certainly does not know.
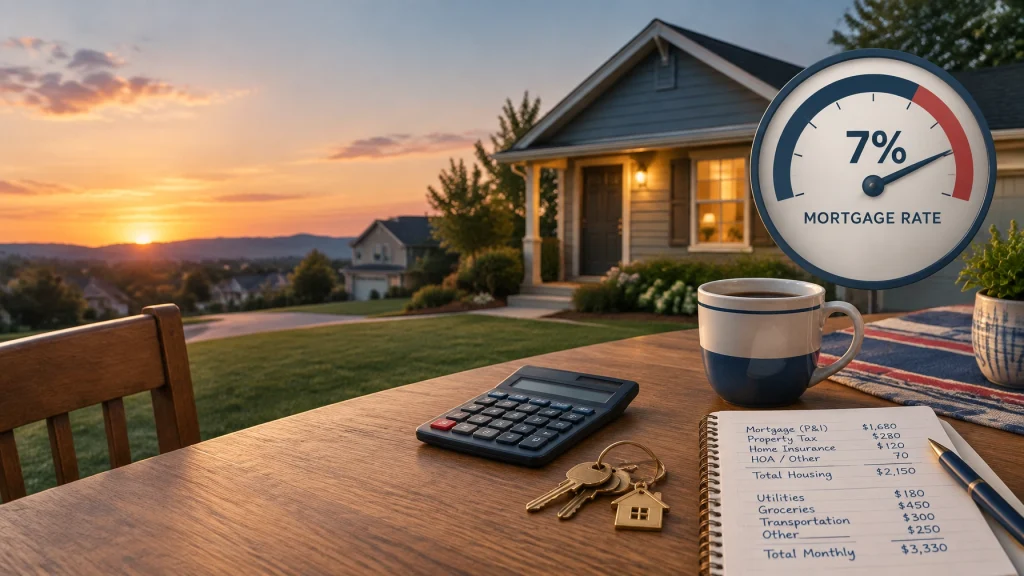
What we do know is that the 30-year fixed mortgage rate has pushed back above 7%.
Daily rate trackers showed conventional 30-year rates around 7.05% to 7.06% on September 17, the highest level in more than 19 months and the fourth consecutive week of increases. Freddie Mac’s weekly survey came in slightly lower at 6.95%, up from 6.76% the previous week and 6.26% a year ago.
That difference is worth understanding: one number is a weekly average, while the other reflects daily lender pricing. Either way, the practical message is the same.
Borrowing a large pile of money to buy a house is expensive again.
First, run the payment math
Take a clean example: a $400,000, 30-year fixed mortgage at 7%.
The principal-and-interest payment is approximately:
- $2,661 per month
- $31,934 per year
- About $958,000 paid over 30 years
- Roughly $558,000 of that total is interest
That is for principal and interest only. Add property taxes, homeowners insurance, mortgage insurance if applicable, and the occasional repair involving a number that makes you question your life choices.
A reasonable all-in housing payment could easily reach $3,100 to $3,300 per month, depending on location, taxes, insurance, down payment, and the condition of the house.
And the $400,000 figure matters. This example assumes a $400,000 loan, not necessarily a $400,000 purchase price. With a 20% down payment, it represents a $500,000 home. With a smaller down payment, the purchase price would be closer to the loan amount, but mortgage insurance and other costs could increase the monthly bill.
Use a mortgage calculator such as Bankrate’s mortgage calculator to replace the national example with your own taxes, insurance, down payment, and loan amount.

Why renting often wins on cash flow
Suppose a comparable rental costs $2,400 per month.
Buying the house could require $2,661 in principal and interest before taxes and insurance. Once those costs are included, the owner may be spending $700 to $900 more per month than the renter.
That does not automatically make renting the better long-term financial decision. Principal payments build equity. The owner may benefit from future appreciation. Rent can rise. The renter does not get to call a plumber at midnight and pretend that counts as wealth creation.
But cash flow is still cash flow.
The buyer also needs to account for:
- Closing costs
- Property taxes
- Homeowners insurance
- Maintenance and repairs
- Possible homeowners association fees
- The opportunity cost of the down payment
- The cost of selling if the buyer moves within a few years
A house is not merely a mortgage payment. It is a mortgage payment wearing a small backpack full of additional bills.
The correct comparison is not “rent versus principal and interest.” It is closer to:
Rent versus the full cost of owning a similar property, adjusted for the equity being built and the length of time you expect to stay.
If renting saves $700 per month, that is $8,400 per year in cash flow. If the buyer would move in three years, the transaction costs and maintenance bills may overwhelm the equity gained. If the buyer plans to stay for 10 or 15 years, the calculation changes considerably.
The market’s opinion is less important than your time horizon.
Waiting for lower rates may be a losing bet
Many buyers were told that mortgage rates would fall in 2026. That prediction has not aged particularly well.
Rates moved higher instead, and economists now broadly expect borrowing costs to remain elevated through the end of the year. Purchase mortgage applications were recently about 19% below the same week a year earlier, according to reporting on Mortgage Bankers Association data.
That does not mean rates cannot fall. It means the calendar is not a strategy.
Waiting can lose in several different ways:
- Rates may not fall as quickly as expected.
- Home prices may rise while you wait.
- Your rent may increase.
- Your income, credit score, or debt load may change.
- The homes available next year may not be as attractive as the homes available today.
There is also a psychological trap here. Buyers often imagine a future in which rates drop, prices remain frozen, sellers become generous, and every desirable house is still available. That is not a forecast. That is a housing fairy tale.
The more practical approach is to establish a payment you can safely afford. If a house works at 7%, buy only if the rest of your life also works at 7%. If the deal requires rates to fall to 5.5% before the payment becomes manageable, the deal does not work today.
A refinance could become available later. It might not. Treat refinancing as a possible bonus, not as the foundation of the purchase.
Who benefits from a 7% mortgage market?
Cash buyers
Cash buyers avoid the largest immediate problem: borrowing costs. They may also have more negotiating power as financed buyers pull back.
That does not mean cash buyers should overpay. A cash offer still ties up capital that could have been invested, saved, or used elsewhere. But in a market where financing is expensive, cash can move a buyer to the front of the line.
Homeowners who locked in 3%
The owners who refinanced or purchased at roughly 3% are sitting on a valuable financial asset. Their mortgage payment is dramatically lower than the payment on a comparable new loan today.
That creates the “golden handcuff” problem. They may want a larger house, a different school district, or a new job in another state. But selling a 3% mortgage and replacing it with a 7% mortgage can blow up the household budget.
Many of these owners are not trapped because they lack equity. They are trapped because replacing cheap debt is expensive.
Builders offering incentives
Builders have tools individual homeowners do not. They can offer:
- Temporary 2-1 rate buydowns
- Permanent rate buydowns
- Closing-cost credits
- Free upgrades
- Price cuts on completed inventory
- Help with mortgage fees
These incentives are increasingly important because builders can reduce a buyer’s monthly payment without publicly cutting every home’s headline price.
Still, read the fine print. A temporary buydown lowers the payment for a limited period. It does not permanently turn a 7% loan into a 5% loan. Ask what the payment becomes in year three, and make sure that number fits the household budget.

Who is stuck?
First-time buyers
First-time buyers face the worst combination: high home prices, high rates, limited savings, and no existing home equity.
The down payment is only the entrance fee. The monthly payment is the long-term test. A buyer who empties the emergency fund to get through closing may own a house but lose the ability to handle a transmission, medical bill, job loss, or broken air conditioner.
Anyone who must move for work
A job transfer does not care whether mortgage rates are convenient. Neither does a family emergency, a divorce, a new child, or the need to care for an aging parent.
For these households, the question may not be “Is this the perfect time to buy?” It may be “What housing choice allows us to function?”
Renting for a year can be a sensible bridge. Buying can also be sensible if the move is durable and the payment is manageable. The key is not pretending that a forced move is the same as a speculative purchase.
Sellers who bought in 2021 or 2022
Some owners who purchased in 2021 benefited from low rates but may have paid aggressively for the house. Those who bought in 2022 may have both a higher purchase price and a higher mortgage rate.
Selling now means confronting today’s affordability math. The next house may cost more than the current house, and the new mortgage may be far more expensive even if the move is only a small upgrade.
That is why existing homeowners are not flooding the market. A large number of them have mortgages that are cheaper than anything currently available.
What should you do?
Start with your own numbers, not the headline rate.
Before making an offer, calculate:
- The full monthly payment, including taxes and insurance
- Your expected maintenance budget
- The cash remaining after closing
- The payment if a temporary buydown expires
- The cost of selling after three, five, or seven years
- Whether your job and family situation support staying put
- The rent for a comparable property
Then ask the least exciting and most useful question in personal finance:
Can this household comfortably afford the payment without needing rates to fall?
If the answer is yes, a 7% mortgage may be unpleasant but workable. Negotiate hard, compare several lenders, ask sellers and builders for concessions, and keep enough cash for life outside the house.
If the answer is no, waiting or renting is not failure. It is refusing to let a real estate agent’s commission schedule dictate your budget.
The housing market does not owe anyone a bargain. But buyers do owe themselves honest math.
Disclosure: This article is for educational and informational purposes only. Regular Guy Economics is not a financial advisor, and this content is not investment, mortgage, tax, or legal advice. Mortgage rates, rents, home prices, and individual circumstances vary. Speak with qualified professionals before making a housing or financing decision.
Be mindful, be watchful and good luck.